Explore Insights & Articles

Discover expert-written articles, investment guides and thought leadership from Planify and our contributors.

​
Top 5 Performing Unlisted Shares of September 2026

23 Oct 2026

5 Min Read

Top 5 Performing Unlisted Shares of September 2026

September was a rough month for Indian stocks. The Nifty 50 dropped 6.06%, its worst September in eight years, but the Primex 40, which tracks unlisted and delisted companies, slid only 1.16%. The private market stayed busy too. NSE finally made its market debut, four other pre-IPO names listed, and Inox Clean Energy filed for a ₹10,000 crore issue. Don't read that as a broad rally, though. Of the 120 unlisted shares whose prices moved, 48 went up and 72 went down.Here are the five names that stood out to me on price action. Three are exchange-infrastructure plays, one is a consumer company heading toward an IPO, and one is a defence-tech firm that shares very little publicly. I ranked them across the 83 unlisted shares that traded in both August and September, so every number below is a clean one-month move.1. ICEX - Up 96.08%ICEX had the biggest jump of the month, ending at ₹5.00. Indian Commodity Exchange runs a commodity derivatives market and competes directly with the listed MCX, with futures in bullion, energy, metals and agri-commodities. Its shareholders include MMTC, Indian Potash and Kribhco, which gives it more institutional backing than most small unlisted exchanges.The report doesn't name a trigger. My guess is that it's riding the buzz around exchange stocks that NSE's IPO created, but that's only a guess. At ₹5, a few small trades can move the price a lot, so I'd call this a thin-trading spike and not proof of real demand.2. CSE Limited - Up 28.57%The Calcutta Stock Exchange is among India's oldest bourses, yet there has been no equity trading on it since April 2013, when SEBI suspended it over compliance, governance and technology issues. Its unlisted shares went from ₹2,100 to ₹2,700 in September, hitting a 52-week high of ₹2,700 on 18 September.This rally has been building since June, when West Bengal's 2026-27 Budget, presented on 22 June, promised support for the exchange's revival. On 1 July, CSE asked SEBI to keep its February 2025 exit application on hold, and the NSE IPO added to the interest in exchange stocks. Still, it's early days. CSE needs a new trading platform and regulatory clearances, and market experts have pointed to hurdles on both the regulatory and business side.3. MSEI - Up 25.95%MSEI, the Metropolitan Stock Exchange of India, is the country's third national exchange after NSE and BSE. Zerodha's Rainmatter and Groww's parent Billionbrains Garage Ventures back it, and it raised ₹1,240 crore over two rounds in December 2024 and August 2025. Its unlisted shares rose to ₹6.95 in September, topped the Primex 40 and touched a 52-week high of ₹7.50 on 14 September.A few developments helped. On 9 September, reports said Groww and Zerodha were testing integration with MSE for cash-market trading, a process expected to take three to four months. Two days later, MSE enabled its first tokenised corporate bond issue, and from 24 September NSE shares were admitted to trade on MSE. Scale is the catch. MSE's daily cash turnover is only about ₹400-500 crore, the broker integrations are still being tested, and there's no IPO timeline yet.4. Furlenco - Up 25.66%Furlenco rents out furniture and home appliances, and its numbers look solid. FY26 revenue came in at ₹370.4 crore, up 61.9%, with a net profit of ₹59.5 crore. The unlisted share climbed to ₹333, a lifetime high it set on 28 September.IPO talk drove the move. On 22 September, reports said Furlenco is planning a ₹1,000-1,200 crore IPO at a valuation of around ₹7,000 crore, targeted for FY28, and the strong listing of rental peer RentoMojo helped the mood. Remember, this is a reported plan and not a filing, and FY28 is a long way off. On that reported valuation, the stock would trade at roughly 118 times FY26 net profit (our calculation).5. JSR Dynamics - Up 23.60%JSR Dynamics is a Nagpur-based defence company that designs and builds airborne guided weapon systems. Boundless Capital took a minority stake earlier this year, with the money meant for expanding capacity and developing new products. The unlisted share rose to ₹11,000 and hit a lifetime high of ₹11,700 on 25 September.Like ICEX, it had no reported trigger for September's move. With so little public information and a share price this high, I'd treat it as a price move first and a story second, and read the company's disclosures closely before drawing any conclusion.The TakeawaySeptember's leaderboard shows where private-market attention went. Three of the five are exchange names (ICEX, CSE and MSEI), helped along by NSE's debut on 24 September. Furlenco is an IPO-bound consumer company, and JSR Dynamics is a defence-tech name with limited disclosure. Two of them, ICEX and JSR Dynamics, moved with no clear catalyst.NSE itself is a good reality check. Its IPO was priced at ₹1,785, about 10% below its last unlisted price of ₹1,990, and by 1 October the shares were trading 1.29% below the issue price. Unlisted shares change hands in thin, negotiated trades rather than through continuous price discovery, so monthly moves often look bigger than they would in listed stocks. Treat them as a rough direction at best, and study each company's financials and background before you put in any money.​

19

0

Read More

Top 5 Performing Unlisted Shares of 2 Quarter of FY2027

23 Oct 2026

4 Min Read

Top 5 Performing Unlisted Shares of 2 Quarter of FY2027

India’s unlisted share market saw mixed performance in Q2 FY27, with INOX Clean Energy leading the top five with a 58% gain, followed by Frick India at 24.5%. NNT Developers (23%), Goodluck Defence and Aerospace (22%) and Garuda Aerospace (over 20%) also posted strong gains, supported by developments such as acquisitions, order inflows, capacity expansion plans and IPO progress.1. Inox Clean Energy Limited - 58% Quarterly gain​INOX Clean Energy, part of the INOXGFL Group, operates in renewable power generation and solar module manufacturing, sectors that could offer significant growth opportunities.The company's acquisition of Vena Energy India for approximately ₹6,000 crore in August, adding 1 GW of renewable capacity and a pipeline of solar and battery storage projects, might have contributed to positive investor sentiment.Additionally, INOX Solar Americas' two solar module supply agreements totalling 1.57 GW in September could have strengthened growth expectations and improved demand visibility in the US market.Its ambitious targets of 10 GW of operational IPP capacity and 11 GW of solar manufacturing capacity by FY2028 might also have supported investor optimism, potentially contributing to its 58% quarterly gain.2. Frick India Limited - +24.5% increase​Frick India could benefit from rising demand for industrial refrigeration and cold-storage infrastructure, driven by growth in food processing, dairy and pharmaceutical industries.Despite pressure on profitability from rising steel, copper and component costs, receivable days improved from 91 to 65, potentially indicating better collections and working-capital management.Its low debt levels may offer financial flexibility, while improving collections could have supported investor confidence. These factors, alongside long-term demand for refrigeration solutions, may have contributed to its 24.5% quarterly gain, although cost control and margin recovery remain key factors to watch.3.  NNT Developers Limited – 23% quarterly gains​NNT Developers Limited, an EPC company focused on civil infrastructure, could benefit from India's growing infrastructure investments.The company secured orders worth ₹423.83 crore during the quarter, taking its order book to approximately ₹856 crore. This strong order inflow may have boosted investor confidence in its revenue growth prospects and contributed to its quarterly performance.Additionally, its DRHP filing for a proposed IPO could have increased investor attention and optimism around the company's future growth potential. Together, the growing order book and upcoming IPO may be among the factors behind its strong performance, although timely execution and profitability remain key challenges.4. Goodluck Defence & Aerospace Limited - 22% Quarterly rally​Goodluck Defence & Aerospace Limited, a subsidiary of Goodluck India, manufactures artillery shells and defense components, positioning itself to benefit from India's growing focus on domestic defense manufacturing.The company's announced investment of ₹500 crore to increase annual artillery shell production from 1.5 lakh to 4 lakh units by September 2027 might have strengthened investor expectations regarding its future growth potential.Additionally, Goodluck India's in-principle approval to merge Goodluck Defense & Aerospace and Goodluck Green Energy into the parent company could simplify the group's corporate structure and strengthen operational integration. This development may further influence investor sentiment, although the merger remains subject to approvals.Rising domestic defense demand and capacity expansion plans might have contributed to the company's 22% quarterly rally. However, successful execution, capacity utilization and profitable order conversion will remain important for sustaining growth.5. Garuda Aerospace - 20%+ quarterly rally​Garuda Aerospace could benefit from growing opportunities in India's drone industry, particularly across defense, agriculture and infrastructure.Its partnership with Australia's Timed Automation Solutions to explore international distribution opportunities and its demonstration of indigenous drone capabilities to the Indian Army may have strengthened its growth prospects.Additionally, Garuda Aerospace received SEBI’s final observations on its proposed IPO in August 2026, clearing a key regulatory step towards listing. This progress could have attracted further investor attention. These developments may have contributed to positive investor sentiment and supported its 20%+ gain, although converting partnerships into profitable business remains crucial.The TakeawayThe top five unlisted shares gained approximately 20–58% during the quarter, reflecting investor interest in renewable energy, defense and infrastructure. However, expansion plans and positive announcements do not guarantee sustainable growth. Investors should assess profitability, valuations and execution risks, particularly given the limited liquidity and price transparency of unlisted shares.Disclaimer: Past performance does not indicate future returns. Unlisted share prices are indicative, can vary across platforms, and may change significantly due to limited liquidity and price transparency. This article is for informational purposes only and is not investment advice or a recommendation to buy or sell any security. Planify facilitates transactions in unlisted shares, including some of the companies mentioned here. Please do your own research or consult a SEBI-registered investment adviser before investing.

9

0

Read More

Hero FinCorp Unlisted Share Price: Complete Investor Guide

18 Oct 2026

5 Min Read

Hero FinCorp Unlisted Share Price: Complete Investor Guide

Hero FinCorp is one of the most closely watched names in the unlisted market, and also one of the most misread. The price has swung hard, the IPO has been “coming soon” for a long time, and the latest numbers don’t look like the growth story people remember. This guide covers what the company does, where the price has been, and what to check before you put money in. What Hero FinCorp doesHero FinCorp started in 1991 as Hero Honda FinLease and took its current form after the Hero MotoCorp restructuring. It lends across retail, SME and corporate segments. Its products include two-wheeler loans, personal loans, business loans, used car finance and equipment finance, sold through 4,000+ touchpoints in 2,000+ locations. The price journeyThe chart of this stock looks like a hill.In December 2023 the share traded around ₹1,257, and by October 2024 it had climbed to roughly ₹2,170.A correction after HDB Financial’s muted listing pushed it to about ₹1,595, and by mid-2026 references placed it near ₹975. One dealer listing currently shows ₹985.Unlisted prices differ from dealer to dealer and change often, so treat all of these as ballpark figures and get a live quote before you decide.Why the price fellThe business went through a rough patch.In FY26, Hero FinCorp reported a consolidated net loss of ₹226 crore against a ₹110 crore profit in FY25. Revenue slipped about 2.5% to ₹9,583 crore.The company paused unsecured lending after NPAs rose and is refocusing on secured products, mainly two-wheeler finance.At its peak the stock was also trading at around 185x trailing earnings, so a lot of optimism was already in the price.Loss figures differ across sources depending on whether they use standalone or consolidated numbers, so check the company’s filings for the exact ones.The one number worth anchoring to: ₹1,400In June 2025, Hero FinCorp allotted 18.57 lakh shares at ₹1,400 each to 12 institutional and corporate investors, raising ₹259.99 crore. That is a real, arm’s-length transaction, which makes it a far better yardstick than a dealer’s quote. At around ₹975, the unlisted price sits well below the last institutional round. That gap could mean the stock is cheap. It could also mean the market has lost faith in the 2025 valuation. The two readings lead to different decisions.IPO statusHero FinCorp filed its DRHP on 31 July 2024 and received SEBI’s observations on 22 May 2025. After the pre-IPO placement, the issue stood at ₹3,408 crore, made up of a ₹1,840 crore fresh issue and a ₹1,568 crore OFS. Reports disagree on the exact status, and no price band or opening date has been announced, so check SEBI’s website for the current position before assuming a timeline.Insights worth your timeAsset quality is the swing factor. Gross NPA improved from 5.45% to 4.23% in FY26, and net NPA from 2.43% to 1.79%. Debt-to-equity also eased from 8.27x to 8.08x. If credit costs keep falling, profits can come back quickly on a loan book of roughly ₹54,000 crore.Value it on the balance sheet, not on earnings. With a loss on the books, P/E means little right now. Price-to-book and the pace of the profit recovery matter more.Expect the IPO price to be lower than unlisted rates. Some dealers say investors expected IPO pricing 30–40% below unlisted market levels, which is why many holders were rushing to exit before launch. That is opinion, not fact, but the earlier HDB Financial listing shows the risk is real.A post-listing lock-in applies. Pre-IPO shareholders face a 6-month lock-in after listing. Listing day is not an exit day.Growth has stalled for now. The loan book grew only about 1% in FY26. The investment case rests on a recovery that hasn’t shown up in the numbers yet.Key risksLiquidity: you can only sell when a buyer is available, and there is no exchange to fall back on.Parent dependence: business is tied to Hero MotoCorp’s performance and the two-wheeler sector.Sector risk: funding costs, asset quality and regulatory changes all hit NBFCs.Timeline risk: IPO dates keep moving, and a delay can leave your money stuck longer than planned.How buying worksYou confirm the quantity and price, share your Client Master Report and KYC, transfer the payment, and the shares reach your demat account, typically within 24 hours of payment confirmation. Buy only through a platform you trust, and check that the shares are delivered to your demat account.TaxUnlisted shares held for more than two years attract long-term capital gains tax of 12.5% without indexation, following the July 2024 Budget change. Gains on shorter holdings are taxed at your slab rate. Confirm your own position with a tax professional.The bottom lineHero FinCorp has a strong parent, a large distribution network and a loan book of real scale. It also has a loss-making year, a paused unsecured book and an IPO with no confirmed date. The current price sits well below both the 2024 peak and the ₹1,400 institutional round. Whether that is a bargain depends on whether you believe asset quality keeps improving. If you invest, size the position so a long wait or a weak listing doesn’t hurt.

10

0

Read More

NNT Developers Limited Files DRHP: Key Details You Need to Know

18 Oct 2026

6 Min Read

NNT Developers Limited Files DRHP: Key Details You Need to Know

The same prospectus has a 24% revenue CAGR, an order book of ₹856 crore and negative operating cash flow. That’s why NNT Developers’ DRHP is worth a good read.The infrastructure contractor based out of Patna has filed its draft papers with SEBI for a mainboard IPO. The offer is a fresh issue of up to 1.72 crore shares with a face value of Rs 10 and no OFS component. Vatsa Capital Venture is proposed to be the lead manager and the shares are proposed to be listed on BSE & NSE. The price band and the dates will be available with the RHP only after SEBI approves the draft.A Bihar company that is outgrowing BiharNNT was incorporated in 2017 and builds roads, railway works, flood-protection structures, water pipelines, public buildings and agricultural market infrastructure, almost always through tenders. Four years ago it was close to a one-state, one-client business. In FY24, Bihar gave it 81.5% of revenue and government departments gave 93%. By FY26, Madhya Pradesh had edged ahead at 47.1% against Bihar’s 44.4%, private clients contributed 42% of revenue, and Nepal added about 6%.Concentration has eased too. The top five customers fell from 85% of revenue in FY24 to 65.7% in FY26, and the single largest customer dropped from 42.3% to 22.1%. The top ten still account for 85.55%, so this is a better-spread business rather than a spread-out one.Growth that did the heavy lifting earlyRevenue rose from ₹144.30 crore in FY24 to ₹223.66 crore in FY26, roughly 24% a year. Profit after tax grew faster, from ₹9.44 crore to ₹21.57 crore, because EBITDA margin widened from 12.36% to 15.21% in FY25 before easing to 14.72% in FY26. PAT margin followed a similar path, from 6.54% to 9.85% and then 9.64%.The easing deserves attention. FY26 revenue grew only 8% after a 43.6% jump the year before, and PAT grew about 6%. The DRHP explains that several large contracts sat at 55–90% completion, where billing waits for milestone certification, and that client payments were delayed near the year-end.On margins, NNT looks good next to the civil-contracting peers the DRHP names. Bondada Engineering earned a 11.49% EBITDA margin in FY26 and Likhitha Infrastructure 12.40%, against NNT’s 14.72%. The DRHP itself warns that competitive bidding can force lower quotes, so whether the premium holds as the company bids for larger contracts is a fair question.The order book is the real storyThe unexecuted order book is ₹856.03 crore across 42 contracts, certified as of August 31, 2026. That is about 3.8 times FY26 revenue. For context, the DRHP’s industry section cites an order-book-to-income ratio of 2.77 for listed railway-sector companies. On paper, NNT has more visibility than its sector.The quality of that visibility is more nuanced. Nearly half the book, ₹423.83 crore, was awarded between July and September 2026, and these contracts have barely started. Revenue from them will depend on how fast NNT mobilises. The book is also lumpy. Three railway contracts, three water supply contracts and three combined building-and-road contracts add up to about 61% of it. The railway trio alone is worth ₹258.8 crore unexecuted, with only about ₹19.5 crore of work done so far.The mix is leaning toward the segments the DRHP’s industry section highlights. Railway is 30.2% of the book, roads 20%, buildings 18.4% and water supply 18%. Private clients make up 46.8%, up from a negligible share a few years ago.One more shift is easy to miss. Bihar holds 73.8% of the order book, while Madhya Pradesh has only about ₹113 crore left, less than one year of its FY26 revenue. NNT’s revenue base will probably swing back toward Bihar over the next two years, which brings the geographic concentration the company has been trying to escape. The company’s own working-capital planning assumes revenue of ₹300 crore in FY27 and ₹550 crore in FY28. These are internal assumptions rather than guidance, and FY28 would need about 83% growth.Profit is not yet cashThe weakest part of the DRHP is cash flow. NNT reported ₹21.57 crore of profit in FY26, yet operating cash flow was negative at ₹1.86 crore, after a negative ₹4.67 crore in FY25. The reason is receivables. Receivable days rose from 28 in FY24 to 152 in FY26, and receivables now stand at about ₹93 crore, close to 42% of annual revenue. The DRHP notes that 81% of this is under six months old.The company has also leaned on suppliers and subcontractors. Payable days rose to 275, and ₹57.12 crore of payables has been outstanding for more than a year. Working capital has moved from 29.7% of revenue in FY24 to 44.75% in FY26, and the company’s own projections push it above 60% in FY28. Growth here is hungry for capital, which explains why ₹75 crore of the IPO goes to working capital.Return ratios show the strain. RoCE fell from about 40% to 33.7%, and RoNW from 26.4% to 21.8%, as the capital base grew faster than profit. They remain healthy, and debt-to-equity is a comfortable 0.39x, but the trend matters.What the industry offersThe demand backdrop is strong. The Union Budget raised public capex to ₹12.2 lakh crore for FY27 from ₹11.21 lakh crore, and railways received a record allocation of about ₹2.93 lakh crore. In Bihar alone, 59 sanctioned railway projects are worth roughly ₹96,651 crore. Jal Jeevan Mission 2.0 runs until December 2028 with an outlay of ₹8.69 lakh crore, which supports the water pipeline contracts in NNT’s book. Bihar’s rivers add a steady stream of flood-protection work.The IPO money and the dilution mathsOf the ₹121.61 crore earmarked, ₹75 crore is for working capital, ₹24.61 crore for machinery and ₹22 crore for repaying bank working-capital loans, with the rest for general corporate purposes. The machinery matters, because owning more equipment lets NNT self-execute more work instead of subcontracting it.The issue is large relative to the existing share base. FY26 EPS of ₹5.39 implies about 4 crore shares today, so 1.72 crore new shares would add roughly 43%. On that rough arithmetic, profit would need to reach about ₹31 crore for EPS to stay flat. Promoters and the promoter group hold 90% before the issue, and a pre-IPO placement is also possible.The takeawayNNT has what many small contractors lack: a full order book, rising private-sector work, strong return ratios and margins above its peers. What it needs to prove is conversion. It must turn an order book that is half brand new into revenue on schedule, and turn that revenue into cash. If it does, FY27 and FY28 could look very different from FY26. If collections stay slow, profit growth will keep outrunning cash. Valuation can only be judged once the price band is announced.

3

0

Read More

Mohan Meakin Limited - FY26 Results

17 Sep 2026

29 Min Read

Mohan Meakin Limited - FY26 Results

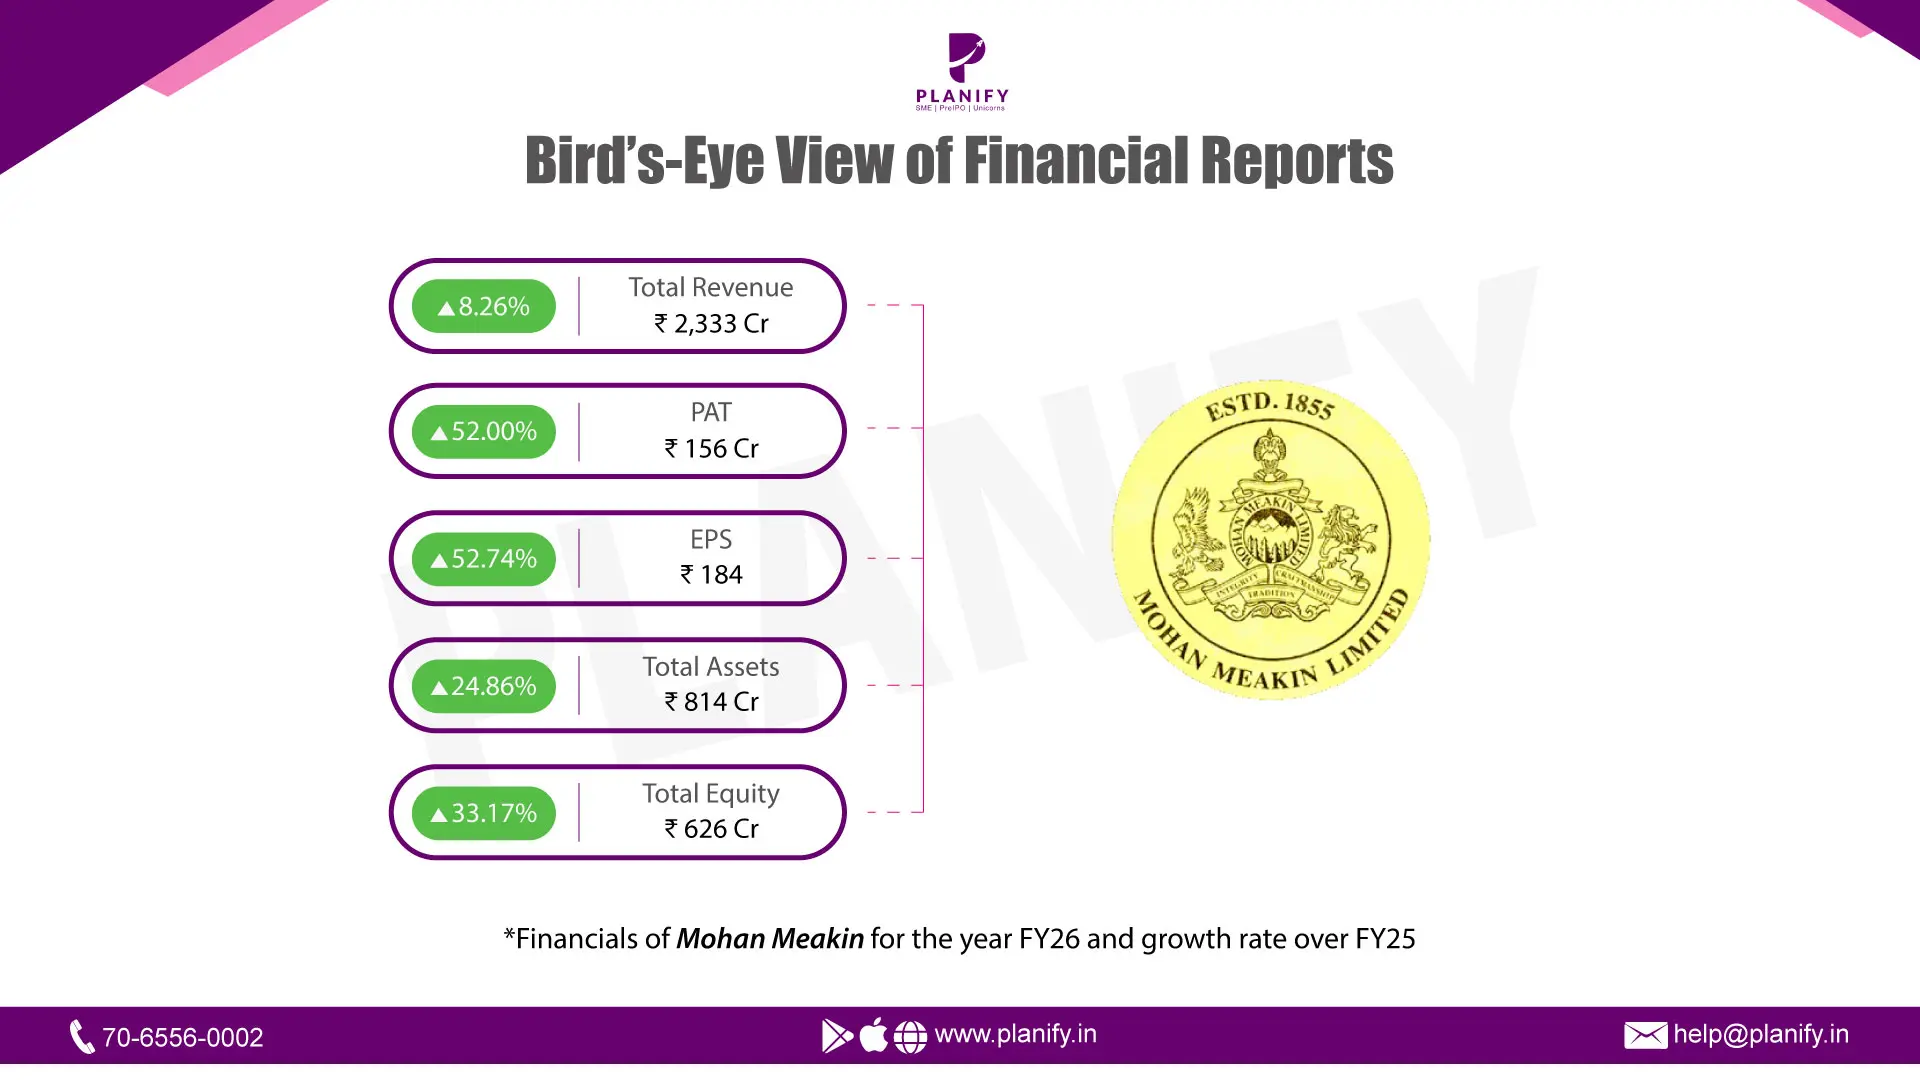
Mohan Meakin Limited, established in 1855, headquartered at Mohan Nagar, Ghaziabad, is among India's earliest alcoholic beverage companies and manufacturer of Old Monk, which is considered the world's best selling dark rum. This company currently has four operational production units, including Solan Brewery (Himachal Pradesh), Kasauli Distillery, Bhankarpur (Punjab), and Mohan Nagar (Uttar Pradesh). Apart from this, it is also involved in the small-scale business of producing non-alcoholic foods and beverages, which include juices, cornflakes, wheat porridge, and vinegar. Since the liquor policies in India are controlled by state governments, Mohan Meakin relies to a large extent on licensed third parties for bottling its product. Shares of this company are listed on the Calcutta Stock Exchange, where there were no transactions during the year, and hence the pricing of shares is done in the grey market.This report contains an analysis of the financial performance of Mohan Meakin Limited for the year ended March 31, 2026 vis-à-vis March 31, 2025. The year 2026 turned out to be a profitable one for the company with revenue from operations growing by a marginal 7.0% to ₹2,302 Cr while profit after tax increasing much faster at 52.7% to ₹157 Cr, driven by a massive swing in the excise duty expense line and a continuing shift in the revenue mix towards the sale of products in which the company did not invest in assets. This resulted in a substantial improvement in both the EBITDA margin (+2.6 pp) and the net profit margin (+2.0 pp). One interesting aspect about the company’s balance sheet is that it had almost no borrowings of ₹4.3 Cr against ₹398 Cr of cash, deposits and investments and was funded mainly by internal accruals.1. Revenue, EBITDA, Net Profit & EPS Summary (₹ in Cr)ParticularsFY26FY25Y-o-Y changeRevenue from Operations2,3022,151+7.0%EBITDA (pre-exceptional)219149+47.0%EBITDA Margin9.5%6.9%+2.6 ppProfit Before Tax209138+51.4%Net Profit (PAT)157103+52.7%NP Margin (NPM)6.8%4.8%+2.0 EPS (₹)184.2120.6+52.7%

73

0

Read More

ASK Investment Managers: The FY26 Profit Crash, Decoded

15 Sep 2026

10 Min Read

ASK Investment Managers: The FY26 Profit Crash, Decoded

India is minting rich people faster than almost anywhere else in the world. The number of Indians with over $30 million in net worth has jumped sharply in the last five years, and India now has over 200 billionaires — third-highest in the world. Deloitte expects professionally managed wealth in India to roughly double by FY29.So here is the puzzle. ASK Investment Managers — one of India's oldest wealth management houses, majority-owned by Blackstone — just closed FY26 with profit after tax collapsing from ₹444 crore to ₹97 crore, a 78% fall. EPS dropped from ₹51.86 to ₹11.67.In the middle of a boom. What happened? We went through ASK's audited FY26 annual report line by line to find out.First, what does ASK actually do?Founded in 1983, ASK holds one of India's earliest discretionary PMS licences (1994). Today it runs ₹77,530 crore in AUM across four distinct businesses — each earning money in a very different way.1. Asset Management — ₹15,446 crore AUM. The original ASK business. It runs listed-equity PMS and AIF strategies for wealthy individuals and family offices, with the flagship Indian Entrepreneur Portfolio. ASK earns a management fee plus a performance fee here. Because ASK manufactures the product itself, this is by far its highest-margin rupee.2. Private Wealth — ₹54,891 crore AUM. ASK's biggest business by size — advisory to 4,300+ HNI/UHNI families through 156 relationship managers. But roughly 74% of this AUM sits in someone else's products (third-party mutual funds, bonds, other AIFs). ASK earns distribution and advisory fees here — far thinner margins than manufacturing.3. Alternates — ₹7,193 crore AUM. Three sub-businesses: a real-estate structured credit fund, a long-short hedge solutions platform, and a newly launched private credit business (Fund I closed at ₹540 crore). These earn fees on committed capital plus performance carry.4. ASK Finance — a small NBFC lending arm earning interest income.Here's the mismatch that explains the entire year: Private Wealth holds 71% of ASK's AUM but contributes only ~18% of fee revenue. Asset Management holds 20% of AUM but drives ~75% of fee revenue.FY26 vs FY25 — the numbers (Consolidated, ₹ crore)MetricFY26FY25ChangeRevenue from operations8691,038−18%Total income9081,112−18%Employee benefits expense371275+35%Finance costs95+79%Depreciation & amortisation2616+56%Other expenses332387−14%Total expenses737683+8%Profit before exceptional items & tax171429−60%Exceptional items7——Profit before tax164429−62%Tax expense67(14) credit—PAT (before minority interest)97444−78%PAT attributable to owners102446−77%Basic EPS (₹)11.6751.86−77%Net worth1,7141,813−5%Revenue fell 18%. Costs rose 8%. That gap is the whole story — but it's driven by four separate things happening at once.Revenue mix — where the ₹169 crore actually went missingRevenue line (₹ crore)FY26FY25Asset management, advisory & other fees649770Financial product distribution & wealth advisory fees156149Fund-based revenue (NBFC)87101Net gain/(loss) on fair value changes(23)18Sponsor contribution(21)20Others(2)(2)Total revenue from operations8691,038Asset management fees alone fell ₹121 crore — that's ASK's highest-margin revenue line, and it accounts for most of the damage. Meanwhile Private Wealth — the part of the business actually riding the industry's growth — grew AUM by ~₹5,800 crore and added 700+ new families, but moved the revenue needle by barely ₹7 crore. A rupee parked in a third-party fund earns a fraction of what a rupee in ASK's own PMS earns.Four reasons behind the fall1. The most profitable machine had a bad year. The Nifty fell ~5% in FY26. PMS/AIF gross inflows collapsed 55% YoY while redemptions rose. Performance fees, which only trigger above a hurdle, dried up.2. ASK's own money lost money. The company holds ~₹1,290 crore of investments on its own balance sheet — largely sponsor commitments required by regulation, plus treasury. "Net gain on fair value changes" swung from +₹18 cr to −₹23 cr, and "Sponsor contribution" swung from +₹20 cr to −₹21 cr — an ₹82 crore negative swing that has nothing to do with client business and everything to do with market moves.3. Deliberate, aggressive spending. Headcount rose from ~500 to 624. ASK hired a new CEO-Equities, a CIO, a Deputy CIO, and a Head of Sales & Distribution; relationship managers rose from 115 to 156. Employee cost jumped from ₹275 crore to ₹371 crore — ₹96 crore of extra salary in the same year revenue fell. On top of the existing business, ASK also funded four brand-new ventures: a mutual fund platform, a DIFC (Dubai) wealth office, a private credit franchise, and a non-discretionary equity advisory desk. Management's own disclosed bridge attributes roughly ₹106 crore of the profit decline to these new, not-yet-profitable initiatives.4. The FY25 base was flattered. In FY25, ASK booked a one-time ₹119.5 crore tax provision reversal (an income-tax refund related to ESOP perquisite deductions), which turned its tax line into a net credit of ₹14 crore — pushing FY25 PAT above its own PBT. Strip that one-off out, and FY25's "real" PAT was closer to ₹325 crore. On that basis, the fall is a still-brutal 70%, not 78% — the headline comparison was never quite apples-to-apples.One more detail: despite the profit collapse, ASK paid out ₹26 per share in interim dividends (~₹227 crore) — more than twice the year's profit — which is why net worth fell from ₹1,813 crore to ₹1,714 crore even though the company stayed profitable.Two different "profits" in the same reportIf you only read ASK's cover page, you'd see ₹277 crore PBT and ₹207 crore PAT — not the ₹171 crore / ₹97 crore in the audited numbers above. Neither is wrong; they answer different questions.Audited profit — what the auditors signed off on. Every rupee earned, minus every rupee spent, minus actual tax paid. This is the legal, real number: ₹171 crore PBT (before exceptionals), ₹97 crore PAT."Matured business" profit — management's own adjusted view, which adds back the losses from the four new initiatives (₹45 crore in asset management, ₹61 crore in wealth — ₹106 crore total) to show what the established business alone earned.₹ croreAudited profit before exceptional items & tax171Add back: losses from new initiatives+106= "Matured business" PBT277Less: exceptional items7Audited PBT164The ₹207 crore "matured PAT" is calculated by applying a hypothetical 25.168% tax rate to the ₹277 crore — it isn't ASK's actual tax bill. The real tax paid was ₹67 crore, and the real PAT was ₹97 crore.Is this misleading? Not necessarily — management's argument is fair: "our core engine earns ₹277 crore; we chose to spend ₹106 crore seeding four new businesses." That's genuinely useful context for a company investing in growth, and ASK does disclose the full bridge rather than hiding it. But three things are worth holding onto: the ₹106 crore is real money that left the bank account; "new initiative" is management's own label, not an audited category; and this framing can, in principle, run for years if the new businesses stay loss-making.How does ASK compare with listed peers?ASK isn't listed — Blackstone owns ~71%, bought in 2022 at roughly $1 billion (~₹7,700 crore). The rest trades on India's unlisted/pre-IPO market. Here's how FY26 stacks up against comparable listed wealth managers (figures independently verified from each company's own FY26 results filings):MetricASK Investment Managers360 ONE WAMAnand Rathi WealthListing statusUnlistedNSE/BSE listedNSE/BSE listedFY26 PAT₹97 cr (−78% YoY)₹1,225 cr (+21% YoY)~₹397 cr (+32% YoY)FY26 AUM₹77,530 cr~₹6.7 lakh cr₹93,037 crApprox. P/E~68x (on reported PAT) / ~33x (on "matured" PAT)~38x trailing~74x trailingApprox. Price/Book~4x~4.8x—Both listed peers grew profit sharply in the same year ASK's fell — a reminder that ASK's FY26 dip is company-specific (its revenue mix and deliberate spending), not an industry-wide problem. On reported earnings, ASK looks expensive relative to 360 ONE WAM; against Anand Rathi Wealth's rich multiple, it's actually cheaper. On book value, all three sit in a broadly similar band.As of late August 2026, ASK's unlisted shares were quoted around ₹785–820, down 35–45% from a 52-week high of ₹1,275–1,485 — the market has already marked this down. With ~8.75 crore shares outstanding, that implies a market cap of roughly ₹6,900 crore. Strip out the ~₹1,290 crore of non-operating investments sitting on the balance sheet, and buyers are effectively paying ~₹5,600 crore for the actual fee-earning business.What could change the story from hereThe mutual fund launch. SEBI's final approval came through in FY26, with schemes going live from August 2026. ASK's PMS minimum ticket is ₹50 lakh, which locks out most of India's wealth — a mutual fund opens the door to everyone and lets ASK "catch" clients early. India's MF industry recently crossed ₹81.5 lakh crore in AUM, growing ~21% — but ASK will be a late entrant (~45th) into an increasingly price-competitive space, especially after SEBI's TER rationalisation.Wealth build-out continuing. RMs are targeted to grow from 156 to 200+ by FY27. A new sub-UHNI segment has already added ~₹1,700 crore; the DIFC Dubai office has pulled in ₹556 crore chasing NRI money; a non-discretionary advisory desk added ₹354 crore in its first year.Alternates scaling. Private credit Fund II got SEBI approval and launched in FY27; the real-estate fund's newest vehicle raised ₹1,350 crore — its largest ever. Alternates fees are stickier than wealth-distribution fees because they're tied to locked-in committed capital plus carry.Operating leverage in reverse. The ₹96 crore of extra salary is already spent and headcount is already in place. If markets recover and revenue comes back, a large share of it should drop straight to the bottom line — but that only works if revenue actually returns.And the elephant in the room: Blackstone typically holds portfolio companies for 4–7 years, and it bought ASK in 2022 — which puts a possible listing or strategic sale somewhere in the 2026–2029 window. Nothing has been announced, but it's a large part of why anyone holds this stock today.Bottom lineASK's FY26 is a useful case study in something people often get wrong about wealth management: AUM growth and profit growth are not the same thing. India's wealth boom is real and shows up clearly in ASK's Private Wealth AUM. But ASK's profits come mainly from manufacturing equity products — a business that is hostage to the Nifty, to gross inflows, and to performance fees that only exist above a hurdle. When markets wobbled, the profit engine stalled, while the boom-facing wealth business added revenue too thin to plug the gap. On top of that, management chose to spend over ₹100 crore building four new businesses into the downturn rather than protect the printed profit number.Whether that turns out to be good judgement will depend entirely on whether the mutual fund, the private credit franchise, and the Dubai office are earning real money three years from now. FY26 was the year ASK paid for its ambition. FY27 onwards is when we find out what it bought.​

18

0

Read More

GKN Driveline India - FY26 Results

15 Sep 2026

4 Min Read

GKN Driveline India - FY26 Results

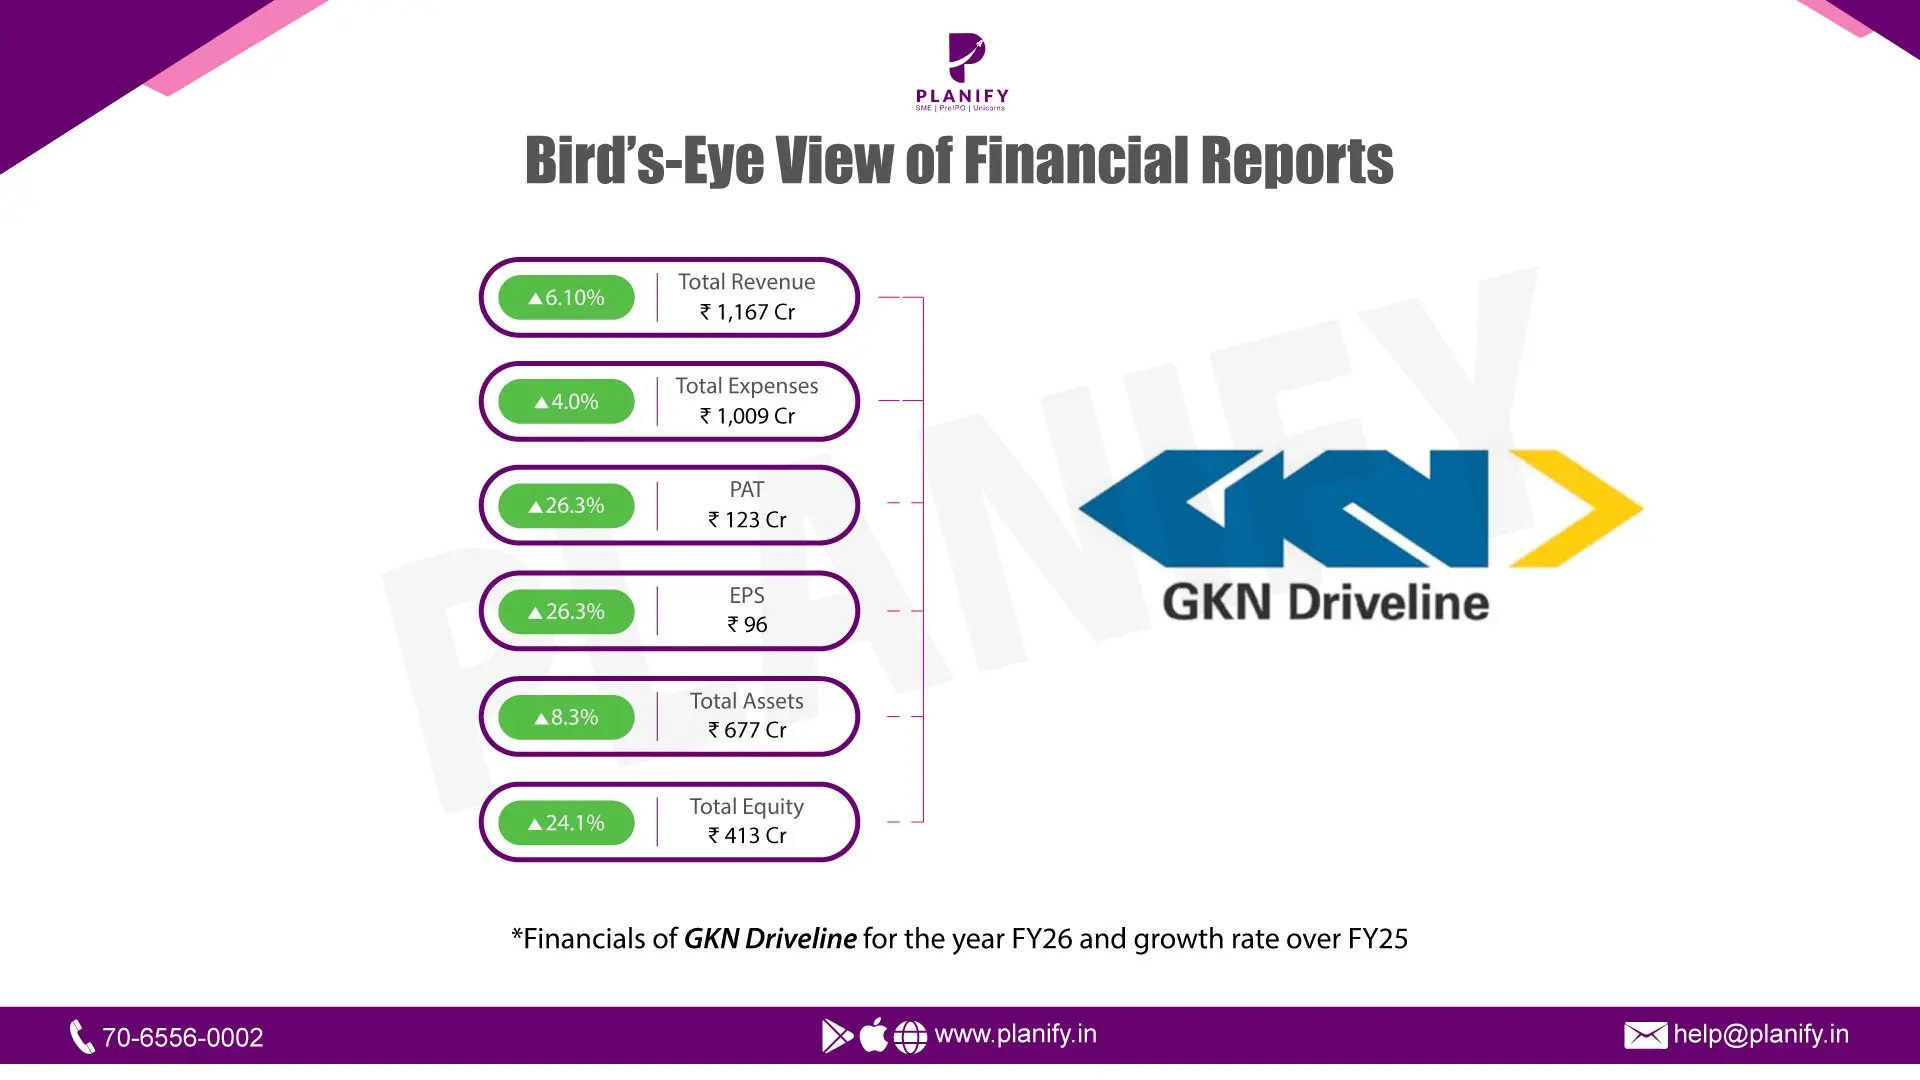
IntroductionGKN Driveline (India) Limited, incorporated in 1985 and headquartered in Faridabad, Haryana, is an automotive components manufacturer and part of GKN Automotive, the global driveline technology and systems business now operating under the UK-based Dowlais Group (demerged from the former GKN plc / Melrose Industries in 2023). GKN Driveline International holds a majority stake in the Indian entity. The company manufactures constant velocity joints, propshafts and connecting shafts, and drive axle assemblies for passenger cars and light commercial vehicles, supplying original equipment manufacturers both in India and overseas, and draws on a technical collaboration with GKN Driveline International, Germany, for its product and process technology. The company operates five manufacturing plants across India.This report presents a summarised analysis of GKN Driveline (India) Limited's financial results for the year ended March 31, 2026, compared with the year ended March 31, 2025. FY26 was a year of profitable growth: revenue grew a modest 6.1% to ₹1,167 Cr, while net profit grew much faster at 26.3% to ₹123 Cr, aided by a decline in cost of materials as a share of revenue and a favourable movement in deferred tax. This drove a meaningful expansion in both EBITDA margin (+2.0 pp) and net profit margin (+1.7 pp). A distinctive feature of the balance sheet is that the company carries no borrowings in either year, funding its operations and growth entirely through equity and internal accruals — total equity grew ~24.1% during the year on the back of retained profits. The analysis below covers headline profitability metrics, a common-size cost structure, key balance sheet items, financial ratios, and a bird's-eye summary, each accompanied by brief commentary highlighting key movements and their implications.1. Revenue, EBITDA, Net Profit & EPS Summary (₹ in Cr)ParticularsFY26FY25YoY ChangeRevenue (Total Income)1,1671,100+6.1%EBITDA209175+19.4%EBITDA Margin17.9%15.9%+2.0 %Net Profit (PAT)12397+26.3%NP Margin (NPM)10.5%8.8%+1.7 %EPS (Basic & Diluted, ₹)96.1276.08+26.3%Revenue grew a modest 6.1%, but profitability grew much faster — EBITDA rose 19.4%, and PAT rose 26.3% — pointing to a genuine improvement in operating efficiency rather than growth alone. EBITDA margin expanded by 2.0% and net margin by 1.7%, aided by lower material costs and a favourable tax outcome, discussed further below.2. Common-Size Statement (as % of Revenue, ₹ in Cr)ParticularsFY25 (₹ Cr)FY25 (% of Rev)FY26 (₹ Cr)FY26 (% of Rev)Revenue (Total Income)1,100100.0%1,167100.0%Cost of materials consumed57652.4%59450.9%Employee benefit expense14313.0%15813.5%Finance costs2.540.2%6.680.6%Depreciation & amortisation423.8%443.8%Cost of materials consumed eased from 52.4% to 50.9% of revenue - the single biggest driver of the margin expansion seen in Table. Employee cost ticked up slightly as a share of revenue, while depreciation stayed flat. Finance costs, though still very small in absolute terms, roughly tripled as a share of revenue (0.2% to 0.6%); given the company carries no borrowings, this rise likely reflects higher lease-related interest under Ind AS 116 rather than fresh debt.3. Key Balance Sheet Items (₹ in Cr)ParticularsFY26 (₹ Cr)FY25 (₹ Cr)Property, plant and equipment257258Inventories11099Trade receivables162136Cash and cash equivalents8966Current borrowingsNilNiNon-current borrowingsNilNilTrade payables (total)184184GKN Driveline's balance sheet stands out for carrying zero borrowings in both years — a genuinely debt-free capital structure. PPE stayed broadly flat, while inventories, receivables and cash all grew roughly in line with or slightly ahead of revenue growth. Trade payables were essentially unchanged YoY, suggesting stable supplier payment terms even as working capital on the asset side expanded modestly.4. Key Ratio AnalysisROE remains strong and broadly stable at around 29-30%, reflecting consistently high capital efficiency. Fixed asset turnover improved further (4.26x to 4.54x), showing the company continues to generate more revenue from its existing asset base. The Debt-to-Equity ratio of 0.00x in both years underscores that all of this growth and profitability was achieved without any reliance on borrowed capital — a conservative and financially resilient profile.RatioFY26FY25YoY ChangeNet Profit Margin10.5%8.8%+1.7 ppReturn on Equity (ROE)29.8%29.2%+0.5 ppFixed Asset Turnover Ratio4.54x4.26x+0.28xDebt-to-Equity Ratio0.00x0.00xNo change​

14

0

Read More

Top 5 Performing Unlisted Shares of August 2026

15 Sep 2026

6 Min Read

Top 5 Performing Unlisted Shares of August 2026

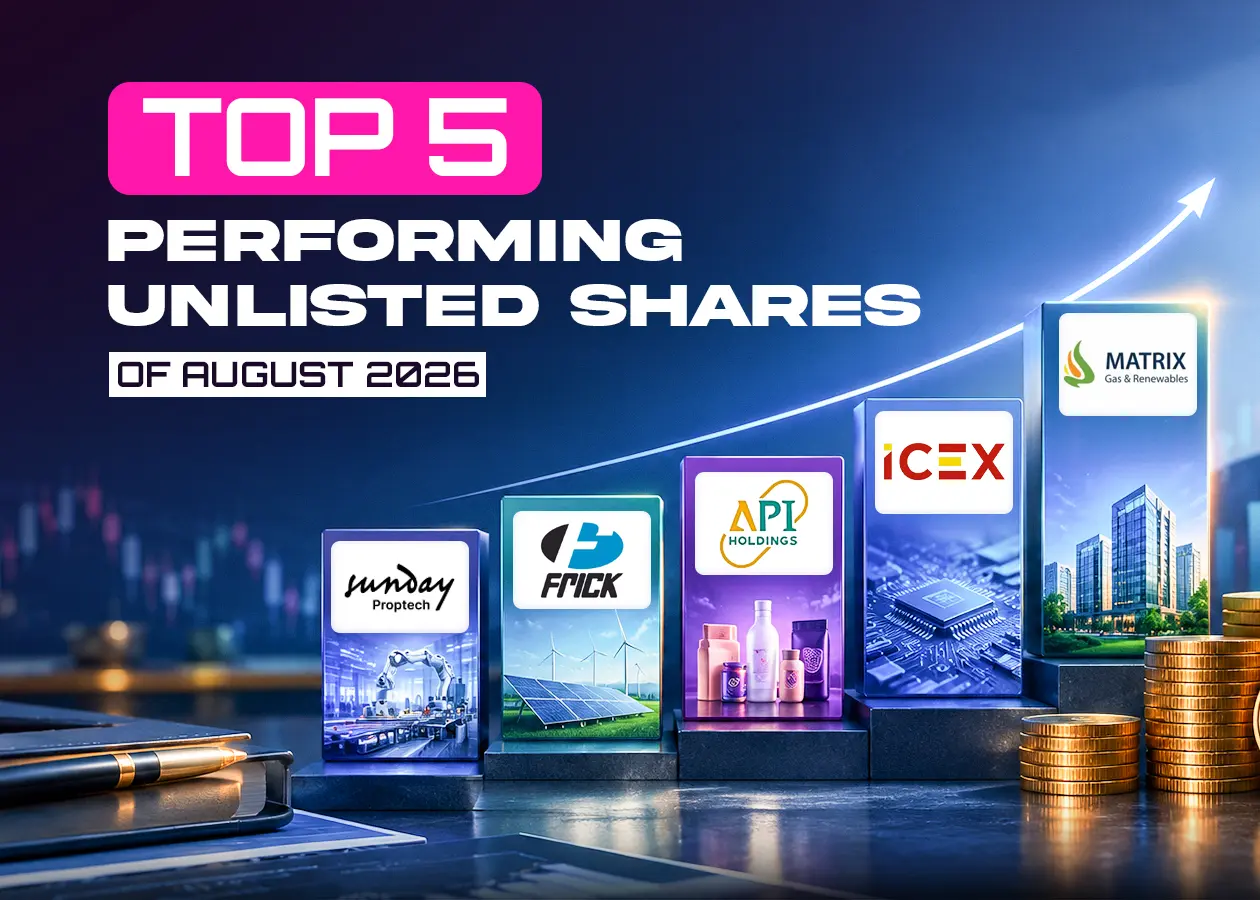
​The Indian Unlisted market had an eventful year, and the month gone by was no different either. SEBI's efforts to legitimize pre-IPO trading, a steady flow of DRHPs, and retail channels making transactions in such names very easy are leading to better volume in the secondary. In light of all this, here are the five names that caught my eye because of their price action during the last month. These are a combination of true pre-IPO stories, speculative plays around exchange infrastructure, and one compounder with a solid fundamentals story.1. Matrix Gas & Renewables - Up 57.9%This month's leader, Matrix Gas & Renewables, holds a sizable edge over others. Formed in 2022 and incorporated in Ahmedabad, Matrix functions as a natural gas aggregator, supplying and marketing natural gas, regasified LNG, and LNG cargoes to industries and commercial clients in the states of Gujarat, Maharashtra, Rajasthan, Haryana, Punjab, Himachal Pradesh, Uttarakhand, and Uttar Pradesh. Besides this core business, Matrix has been expanding into a parallel growth opportunity in green hydrogen and green ammonia, including manufacture of electrolysers and EPC/BOO projects.Rallying in price this month, the stock follows in line with a renewed pre-IPO buzz – it has already filed draft documents for a listing on the NSE Emerge and has earlier secured funding from a range of investors including Ashneer Grover (co-founder, BharatPe) and other venture and family office funds. However, there is a history of sharp corrections here too – the stock has declined over 50% from its all-time high seen in April 2025 on account of IPO pricing being lower than expected in the grey markets. Promoter linkages to the Gensol Group are another key element to keep in mind.2. Indian Commodity Exchange (ICEX) - Up 40.8%​ICEX is the derivatives exchange for commodities and the direct competitor of the publicly listed Multi Commodity Exchange (MCX). It provides for futures trading in the sphere of bullion, energy, metals, and agri-commodities. The shareholders include prominent institutional entities like MMTC, Indian Potash, and Kribhco, along with private investors, which adds some credibility to ICEX as an exchange, a quality that is somewhat uncommon for small unlisted exchanges. ICEX has experienced some problems in its business operations, including multi-year trading suspensions in the past. However, it has been trying lately to position itself as an IPO candidate due to increased interest in exchanges as infrastructure from retail clients (the same trend has fueled NSE and MSEI unlisted stocks this year).The 40.8% increase this month seems to be primarily driven by the aforementioned IPO speculation rather than any particular financial event — financials of ICEX have been little known to date, which should be noted. Furthermore, commodity exchanges are essentially volume-dependent, and there cannot be any simple transfer from NSE and MCX performance to ICEX. It is a company for investors who can support the IPO hypothesis with no clear financial visibility.3. API Holdings (PharmEasy) - Up 34.6%​PharmEasy, which owns one of India's largest digital pharmacies and health tech platforms, is showing another step in its comeback story. This company had to face a big decrease in its valuation several years ago because of a tough financing environment and the negative effect of the Thyrocare acquisition, but since then, the firm has been slowly recovering through better margin control and reduction in losses. This month's development looks like it is connected with growing expectations about the IPO attempt and investors' preparation for a potential filing.The business model is strong enough from a structural point of view – there are a lot of opportunities for PharmEasy as the penetration level of organized pharmacies and the diagnostics market in India is still relatively low despite the country's population and the way healthcare expenditure will evolve. However, the re-rating of this stock looks like it is happening way faster than any IPO filing, and the history of high expenses of the company makes IPO price one of the most important factors here.4. Frick India - Up 24.5%In terms of the fundamentals story, there is one name which stands out: Frick India. This firm is India's largest producer of industrial refrigeration and air-conditioning equipment and traces its roots back to a technical cooperation from 1962 between Frick Company, USA, and itself. It provides a complete range of services from design, production, installation, and after-sales servicing. The main market for the firm lies in dairy and food industries, as well as cold chain logistics. Given the fact that India is the largest producer of milk and a significant exporter of fruits and vegetables, it representsa very good business opportunity.While the other stocks mentioned above are largely a product of speculative activities of their owners, the growth in Frick India shares is based on actual positive results in revenues and profits of the company, along with rising EPS and dividends paid regularly. Thus, for those who are afraid of pure IPO speculation, this company can be seen as the best alternative among the firms listed here.5. Sunday Proptech - Up 23.4%Coming up fifth place on our list is the relatively small-cap Sunday Proptech, which has been seeing some pickup in activity on the secondary market this month. It’s certainly part of a trend toward growing interest in real-estate technology and fractional-ownership platforms, a sector which has gained increasing traction among Indian retail and HNI investors as SEBI seeks to regulate fractional real estate ownership. On the other hand, when compared with the other companies mentioned on this list, information available on Sunday Proptech is relatively scarce.This may be considered a blessing and a curse. While it certainly could suggest undervaluation in this case if the company is performing well, it does leave investors with much less to go on when valuing the stock’s current price action.The TakeawayThe leaderboard for the month gives a decent idea of the current state of sentiment in the Indian private equity market: real IPO stories backed by filings (Matrix Gas, PharmEasy), an overvalued infrastructure-for-exchange concept without any known fundamentals (ICEX), an earnings-backed compounding story (Frick India), and a niche player that fits into a wider market theme (Sunday Proptech). The key thing to keep in mind is that private shares are priced through low-volume negotiated trades in secondary markets, not via ongoing price discovery on exchanges, which means that any monthly change in prices, positive or negative, is usually more pronounced than what one might see in a listed security. Any potential investor interested in any of these companies should take their performance in the month as a directional hint, at best, and dig deeper into the financials and backgrounds of these companies before committing any money.

72

0

Read More

MSE just facilitated India's first tokenised corporate bond. The headline isn't the real story — the balance sheet is.

15 Sep 2026

6 Min Read

MSE just facilitated India's first tokenised corporate bond. The headline isn't the real story — the balance sheet is.

On 11 September 2026, Metropolitan Stock Exchange (MSE) announced that its Electronic Bond Platform (EBP) had processed a tokenised corporate bond for IIFL Finance, under SEBI and RBI's new "Demat 2.0" pilot — launched jointly by SEBI Chairman Tuhin Kanta Pandey and RBI Governor Sanjay Malhotra at the Global Fintech Fest.If you track MSE's unlisted shares, this read like the breakthrough moment. It isn't — or at least, not on its own. Here's why, and what actually matters instead.First, what is an EBP — and why does it exist?When a company wants to raise ₹50–500 crore through bonds, it usually doesn't do a public issue — it places the bonds privately with a handful of institutional investors. Before 2016, this happened over phone calls between the CFO and a few fund managers, with no visibility into who got what price. SEBI's Electronic Book Provider (EBP) framework put this process on a public screen instead: issuers notify the market, investors bid, and the system allots bonds to the lowest-cost bidders first.Since May 2025, using an EBP is mandatory for any private bond placement of ₹20 crore or more (down from ₹50 crore) — and since well over 90% of India's corporate bond issuance is private placement, this isn't a niche rule. NSE, BSE and MSE have all held this EBP licence since it launched on 1 July 2016.What Demat 2.0 actually changesOn 10 September 2026, SEBI and RBI launched a regulatory sandbox pilot to test tokenised corporate bonds. Three issuances have gone through so far, totalling ₹1,025 crore:IssuerDateAmountInvestorsREC Limited7 Sept₹500 cr18Larsen & Toubro9 Sept₹500 cr4IIFL Finance9 Sept₹25 cr1The bidding process, the ₹20 crore threshold, the ISIN, and the bond's legal character are all unchanged — SEBI has been explicit that tokenisation doesn't create a new asset class or a safer instrument. What changes is what happens after allotment: the bond exists as a digital token on a ledger owned by India's depositories, settlement runs through RBI's wholesale CBDC (e₹), and both legs — cash and securities — settle atomically, on the same day, instead of the usual T+2. Coupons and redemptions can eventually be automated through smart contracts.Crucially, this back-end upgrade was handed to NSE, BSE and MSE simultaneously. MSE facilitating the IIFL deal is a genuine first — but it's not an exclusive technological edge. Secondary trading and retail access are both still pending, with no date announced, and only 23 investors have participated across all three deals so far.So why is this MSE news at all, if the tech is shared?Because the real story sitting underneath the press release is what's happened to MSE's balance sheet over the last 20 months — and it's a much bigger deal than one ₹25 crore bond.MSE has held its EBP licence since 2016. In FY26, its entire operating revenue was ₹3.4 crore, against a net loss of ₹25.8 crore (an improvement from ₹34.2 crore the year before, but still a loss). For a decade, NSE built commanding share in this business — it now holds roughly 95% of the debt RFQ market — while MSE barely registered. That wasn't a technology gap or a regulatory gap; MSE always had the same licence NSE did. It was a resourcing gap: a loss-making exchange simply couldn't afford to hire and retain the relationship bankers that bond issuers actually pick platforms based on.That constraint has now changed dramatically. Over two rounds:December 2024 / January 2025: MSE raised ₹238 crore, with Billionbrains Garage Ventures (Groww's parent), Rainmatter Investments (Zerodha founders' fund), Share India Securities and Securocorp Securities India each taking roughly equal stakes at ₹2/share, pegging MSE's valuation near ₹1,200 crore.August 2025: MSE raised a further ₹1,000 crore, this time from a much broader consortium — Peak XV Partners, Trust Investment Advisors, Jainam Broking, Monarch Networth, and several other brokers and funds.Total raised: roughly ₹1,238–1,240 crore — about 365 times MSE's annual operating revenue. Total equity jumped from ₹396.69 crore in FY25 to ₹1,369.29 crore in FY26. MSE's stated priority for this capital is to deepen liquidity in its equity cash segment first, then derivatives — the bond platform isn't even the headline use of funds. But it does mean MSE can now afford the one thing it never could before: a real relationship-driven debt capital markets desk, without betting the company on it.Why Zerodha and Groww specifically matter hereA ₹59.5 crore cheque each is small change for either firm. The more interesting angle is what they represent: between Zerodha's roughly 6.5 million and Groww's roughly 13 million active investors, MSE's cap table now includes two of India's largest retail distribution networks.That matters because Demat 2.0's later phases are explicitly aimed at retail access to corporate bonds — and tokenisation makes fractionalising a bond into small, retail-sized tickets technically straightforward. If and when that phase arrives, distribution reach — not exchange infrastructure — decides who actually gets those bonds in front of retail investors. Two of India's biggest brokers already sit on MSE's shareholder register.There's also a credibility effect that's easy to underrate: a bond arranger deciding whether to route a deal through MSE is implicitly asking "will this platform still be relevant in three years?" A decade of losses made that a fair question. Backers like Rainmatter, Groww's parent, and Peak XV Partners change that calculus.One more detail worth flagging: Trust Investment Advisors — the arranger on the very IIFL tokenised bond in the press release — was also one of the 29 investors in MSE's August 2025 fundraise. That's not proof of anything improper; arrangers investing in exchange platforms they work with isn't unusual. But it's a clean illustration of exactly the dynamic described above — capital and relationships arriving together.What this doesn't meanCapital buys hiring capacity, not a decade of trust. Treasurers who've routed every bond issue through NSE since 2018 don't switch platforms because a new VP joined MSE.The bond desk may stay a secondary priority — MSE's own language points to the equity cash segment and derivatives as the primary use of the new capital.Demat 2.0 is still a sandbox pilot: no secondary trading yet, no retail access yet, and no announced timeline for either.NSE isn't standing still — it received the same infrastructure on the same day and can match fee cuts easily out of its existing scale.What to actually track over the next few quarters: EBP results are published publicly by every exchange. The number that matters isn't the press release — it's how many bond issues, month over month, start landing on MSE's platform versus NSE's and BSE's, and whether MSE visibly builds out a debt capital markets team. Everything else is narrative.

10

0

Read More

Stay Connected, Stay Informed –

Join Our

WhatsApp

Channel!

Don’t miss out on exclusive updates, market trends, and real-time investment opportunities. Be the first to know about the latest unlisted stocks, IPO announcements, and curated Fact Sheets, delivered straight to your WhatsApp.

planify

Planify Enterprises Private Limited
Planify Capital Limited

Licensed By

india
AMFI
MFU
startupIndia
IosAppAndriodApp

Registrations & Certifications

Mutual Fund License No.:

ARN-164419

IRDA Code (1):

ABLIC1003123454

IRDA Code (2):

ABLIC1003131639

Startup India Certificate No.:

DIPP93786

Other Websites

Address

MiQB, Plot 23, Sector 18 Maruti, Industrial Development Area, near Motherson Sumi Systems Limited, Gurugram, Haryana 122015

ⓒ 2016-2026 Planify. All rights reserved, Built with 

 in India

planify

MiQB, Plot 23, Sector 18 Maruti, Industrial Development Area, near Motherson Sumi Systems Limited, Gurugram, Haryana 122015

Mutual Fund License No.

ARN-164419

IRDA Code (1):

ABLIC1003123454

Startup India Certificate No.

DIPP93786

IRDA Code (2):

ABLIC1003131639

Licensed By

indiaAMFIMFUstartupIndia

Stay Connected With Us

through our iOS and Android apps for an on-the-go investing experience. Download our apps today App Store or Google Play Store.

AndriodAppIosApp
facebookwhatsappXlinkedinyoutubetelegraminstagrampinterest

ⓒ 2016-2026 Planify. All rights reserved, Built with ❤️ in India