Bombay Gas Company Limited: From Gas Pipelines to Fibre to a ₹23 Crore Lending Business
Kratika Agrawal
Associate Financial AnalystFinancial Analyst at Planify with CFA L2 credentials, focused on valuation modeling and identifying growth opportunities across unlisted and pre-IPO equities.
Category
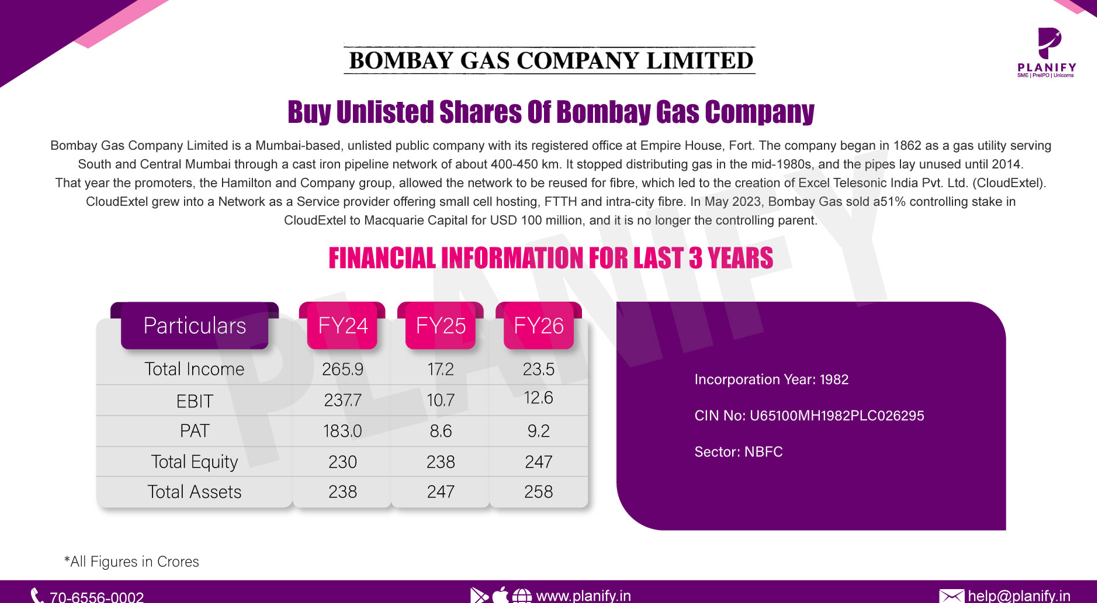
The Bombay Gas Company Limited (BGCL) is not into the business of supplying gas anymore. After selling the stake in its fiber-telecom business called CloudExtel in 2023, BGCL has now turned into a lending and investment company. Bombay Gas Company’s unlisted shares now represent a profitable, nearly debt-free lending and investment business, but the revenue it generates is quite minimal.
What does Bombay Gas Company do today?
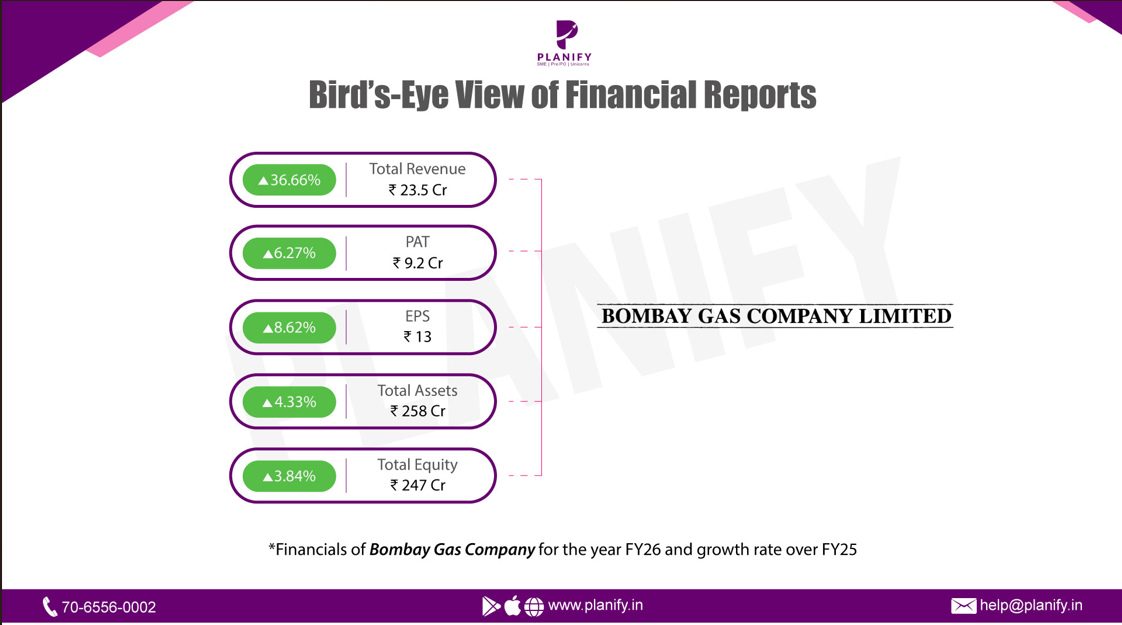
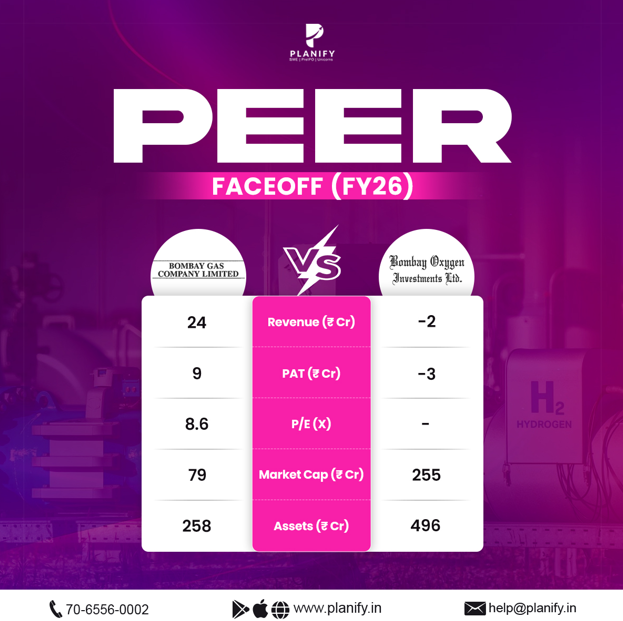
Bombay Gas Company Limited (BGCL) is an unlisted lending and investment company. After selling a majority stake in its fiber business, CloudExtel, in 2023, it earned ₹23.52 crore of revenue and ₹9.15 crore of net profit in FY26, mostly from interest income. Its shares trade at a P/E of 8.67, about 47% below the sector.
How BGCL went from gas pipelines to CloudExtel
The deal has been closed in May 2023, where CloudExtel sold a 51 percent majority stake for $100 million, buying out the shares of Bombay Gas Company.
Bombay Gas Company financials: FY21–FY26
FY21 | FY22 | FY23 | FY24 | FY25 | FY26 | |
Revenue | 57.20 | 83.38 | 128.91 | 265.88 | 17.21 | 23.52 |
EBITDA | 16.23 | 18.06 | 26.70 | 237.75 | 10.75 | 13.06 |
Net income | −6.90 | −9.09 | −23.62 | 182.99 | 8.61 | 9.15 |
EPS (₹) | −8.63 | −11.36 | −29.54 | 228.74 | 12.18 | 13.23 |
FY21–FY23: growing revenue, mounting losses
Money Making and Losing. Revenue increased by 46% and then by 55% per annum while the loss for the period was ₹39.6 crore. The company made operating profit, however, the depreciation charges and interest on the network increased from around ₹20 crore to around ₹38 crore per annum and eliminated the profits. This is very common for an infrastructure-heavy business.
FY24: the year of exit
The company’s revenue soared to ₹265.88 crore and net income increased to ₹182.99 crore. There were negligible amounts of depreciation and interest expenses, as the network had exited the company’s books. It was a one-off year.
FY25–FY26: a smaller, steadier company
A leaner but consistent firm. Revenues range from ₹17 to ₹23 crores. FY25 profits were ₹8.61 crores while FY26’s were ₹9.15 crores. FY26 saw a 37% increase in revenues, but only a 6% increase in profits, net margins declined to 39%
Where BGCL’s FY26 income comes from
Source | ₹ crore | Share |
Interest on loans, bonds, NCDs, FDs | 13.99 | 60% |
Profit on sale of long-term investments | 5.09 | 22% |
Sale of shares and securities | 3.27 | 14% |
Dividend on stock held as inventory | 0.43 | 2% |
Dividend on investments | 0.29 | 1% |
Rent, compensation and service charges | 0.15 | 1% |
Income from guarantees provided | 0.04 | 0% |
1. Interest income dominates
It is a savings and lending institution. Six out of every ten rupees earned comes from interest income. With interest rates between 8 and 10 percent, ₹14 crore of interest income amounts to around ₹140 to ₹175 crore in investments.
2. Recurring vs market-linked income
Approximately two-thirds of the income is regular in nature. The interest, dividends, rents, and guarantee fees total ₹14.90 crore, i.e., 64% of income. Another 36%, which totals ₹8.36 crore, is the income from sale of investment and shares, which is market-sensitive.
3. Profit without the one-off gain
The profit after deducting the one-time gain will be lesser. The net profit excluding the gain of ₹5.09 crore on long-term investments will be ₹7.5 crore compared to ₹12.6 crore. At the rate of taxation of FY26 being approximately 27%, this amounts to ₹5.5 crore, or ₹8 per share compared to ₹13.23 per share.
4. Dividends are negligible
It comes to only ₹0.72 crore, which is just 3% of the income. BGCL does not receive any significant dividend income from its investments.
5. Costs are high for a finance company
The expenses are high for a finance company.The expenses have taken about 46% of the FY26 revenues: cost of sales is ₹5.34 crore and operating expenses are ₹5.12 crore. Depreciation and interest charges are virtually negligible.
6. BGCL also provides guarantees
While the fee income is just ₹4 lakh, it clearly indicates that BGCL is providing guarantees for obligations of others.
Bombay Gas Company share price and valuation
The P/E of the company stands at 8.67, which makes it appear undervalued compared to any profitable financial services firm. The Nifty Financial Services Index is the most widely used index for the financial services sector and has been trading at a trailing P/E of approximately 16.4 in mid-November 2026, while having a median P/E of 17.6 over the past five years. This makes the stock trade at about half of the sector average P/E, a discount of approximately 47%. This discount could be attributed to the small-cap nature of the firm and its illiquidity, as the promoters own 88.58% of the company.
Ownership and governance
BGCL is a promoter-driven organization. Sushil Kumar Jalan is the managing director of the firm, Ashish Jalan is the director of the organization since 2009, while Arvindkumar Kanoria is another director of the company. The 42nd annual general meeting of the company was conducted on 30th September 2024, while the most recently recorded annual general meeting was on 11th August 2025. Thus, annual general meetings are conducted annually.
Strengths and risks of Bombay Gas Company unlisted shares
Strengths
- It transformed a dormant pipeline network to become a $100 million company and made a successful exit.
- It has been making money in the past three years in a row.
- It has very little debt and almost zero depreciation.
- Most of its revenue comes from interest and dividends.
Risks
- Approximately 36% of revenue is derived from investments and sales of shares, hence making EPS volatile each year.
- Profitability on capital deployed is low.
- The guarantees it gives to others might have some hidden risks.
- Share price is irregular since the stock is not listed.
- It is family-owned, with limited disclosures.
- Costs of operation are relatively high as compared to those of an average borrower.
Conclusion
Bombay Gas Company Limited has an old name, a smart history, and a new life as a lending and investment company. It is stable, lightly leveraged, and profitable but small. Its value now depends on the quality of its loans and investments and on how the family manages the cash from its CloudExtel exit.
Disclaimer: This article is for information and education only and is not investment advice or a recommendation to buy or sell any security. Unlisted share prices are indicative. Unlisted shares carry high liquidity and valuation risk. Please consult a SEBI-registered investment adviser before investing.
Tags
Stay Connected, Stay Informed –
Don’t miss out on exclusive updates, market trends, and real-time investment opportunities. Be the first to know about the latest unlisted stocks, IPO announcements, and curated Fact Sheets, delivered straight to your WhatsApp.