OYO Unlisted Shares Rise 26% — Will the IPO Match Expectations?
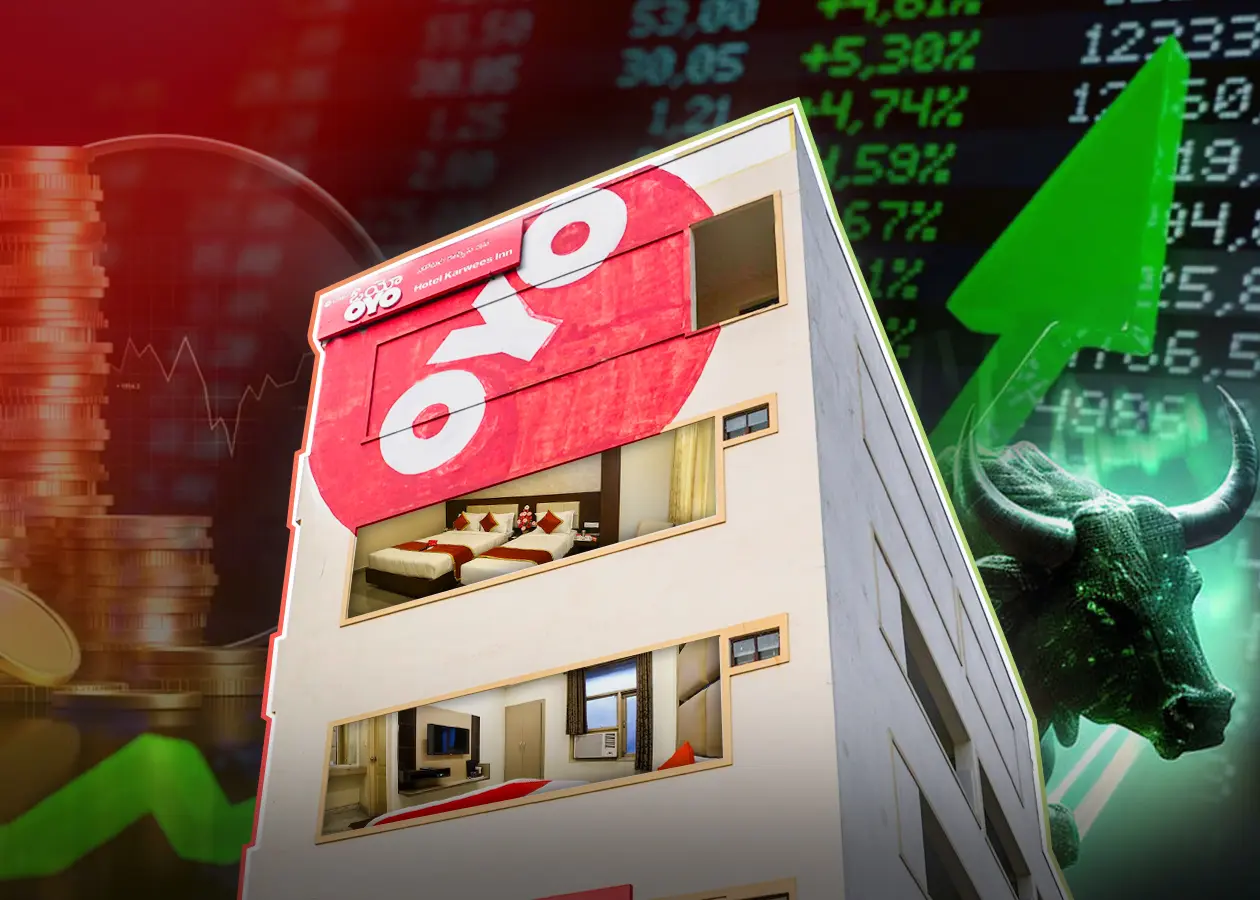
In a remarkable turn of events, OYO's unlisted shares have surged by 26% in the past and last month, which resulted in reigniting the conversation around its long-awaited IPO. This rally, which has outpaced several listed hospitality peers, has been fueled by a mix of market buzz, improved financial performance, and sort of strategic tricks & strategic moves by the company. The question now is whether this momentum will carry into the public market, and whether OYO’s IPO can live up to expectations of a $7–8 billion valuation.
Why are OYO unlisted shares rising?
OYO unlisted shares rose about 26% in a month on four triggers: reports that it would refile its DRHP in November, its first annual profit in FY24 and about ₹200 crore of Q1 FY26 profit, a push into premium hotels such as Sunday, and a 1:1 bonus issue with a 30 September 2025 record date.
1. IPO buzz: DRHP refiling expected
News reports suggest OYO is preparing to refile its Draft Red Herring Prospectus (DRHP) in November, which quickly set off a wave of buying in the unlisted market. After two shelved attempts, this third push is being read as a sign of OYO’s new maturity and stability.
2. First annual profit and Q1 FY26 growth
OYO reported its first-ever annual profit in FY24. In Q1 FY26, profit after tax was about ₹200 crore, more than double the same quarter a year earlier. For a company with a history of heavy losses, the turnaround signals to investors that its asset-light model is starting to pay off.
3. Premiumization: Sunday and Check-In
OYO’s shift towards premium properties is gaining traction. The company is expanding its premium hotel brand, Sunday, and recently launched a vertical focused on upscale properties. The aim is to raise revenue and improve margins, which have historically been thin in the budget segment.
4. 1:1 bonus issue
A 1:1 bonus share issue with a record date of 30 September 2025 also boosted demand, as investors rushed to buy shares before the cut-off.
OYO at a glance: key numbers
OYO key numbers, as of September 2025
Metric | Figure |
|---|---|
Unlisted share price move | +26% in about a month |
First annual profit | FY24 |
Q1 FY26 PAT | ~₹200 crore (more than 2x year on year) |
Bonus issue | 1:1, record date 30 September 2025 |
Unlisted P/E | ~150–160x |
Lemon Tree Hotels P/E | ~50x |
Margins | ~6–7% |
Valuation expectation | $6–8 billion |
IPO attempt | Third (after two shelved attempts) |
OYO’s parent rebrands as PRISM
Alongside its push for financial discipline, OYO’s parent company, formerly Oravel Stays, has rebranded as PRISM. The new name reflects a global portfolio that spans hotel brands, vacation homes, branded residences and technology tools for partners, and it signals a strategy built on clarity, diversity and long-term positioning.
PRISM’s tech tools give hotel owners analytics on pricing, performance and customer trends. This data-led approach improves partner retention and revenue optimisation, which matters as OYO looks to sustain margins and justify its IPO valuation.
OYO valuation vs listed hotel peers
At current unlisted prices, OYO trades at forward multiples far higher than traditional hotel chains. Investors are essentially paying for scale, tech-driven efficiency, and asset-light growth - qualities that traditional hospitality chains cannot match.
According to unlisted market estimates, OYO is trading at P/E multiples in the ~150-160× range, significantly higher than listed hotel chains such as the phenomenal name includes Lemon Tree Hotels, whose P/E is ~50×. Investors paying the premium are betting on OYO’s scale, asset-light model, and margin expansion, though much depends on a lot of continuous and sustained financial performance and clarity post-IPO.
Risks and concerns: However, this premium comes with risk. OYO’s margins, at around 6–7%, are still thin compared to global benchmarks. The history of its debt status and disputes with the hotel partners also raises questions. To give long -term value to IPOs, OYO will need to display that the profitability is durable in cycles, not just during travel upswings.
The strong recovery of the global tourism industry provides a strong tailwind for OYO's expansion plans, especially in terms of its international markets.
However, skeptics indicate to remain cautious. The high valuation comes with significant risks. OYO's ability to maintain its profitability and sustain its growth in a highly competitive market will be under intense scrutiny and consistent rapid investigation. The company also faces ongoing legal and regulatory challenges, including a fine from the Competition Commission of India and various service tax disputes. These issues can eat in future profits, with a heavy debt burden and cause financial vulnerability. In addition, the previous performance of the recent Indian tech IPO has been mixed, with some, like Paytm and Zomato, seeing significant corrections after their listing.
Can the IPO Match Expectations?
Given the data, it is possible though not guaranteed that OYO could deliver a strong IPO. The recent unlisted share bump, improving profit trends, bonus issue move and board-level IPO preparation suggest OYO is improving its financial and governance posture. If it files in November as many reports expect, there will likely be strong institutional demand.
However, for OYO to truly justify a $6-8 billion valuation (or higher), it will require to do more than post rising topline. It must maintain/improve margins, reduce debt or manage financing costs well, alongside other tasks and navigate regulatory risk, and show growth in diversified markets. Any misstep weaker than expected revenue growth, overspending, legal surprises could lead to valuation compression once the IPO opens.
OYO unlisted shares FAQ
1. Why did OYO unlisted shares rise 26%?
Because of reports that OYO would refile its DRHP, its first annual profit in FY24 and stronger Q1 FY26 profit, its push into premium hotels, and a 1:1 bonus issue.
2. When is the OYO IPO?
As of September 2025, reports suggested OYO would refile its DRHP in November 2025. It would be the company’s third IPO attempt.
3. What is PRISM?
PRISM is the new name of OYO’s parent company, formerly Oravel Stays. The name covers its hotel brands, vacation homes, branded residences and partner technology tools.
4. What was the record date for OYO’s bonus issue?
30 September 2025, for a 1:1 bonus share issue.
5. Is OYO expensive compared with listed hotel companies?
On unlisted market estimates, OYO trades at a P/E of about 150–160x, against about 50x for Lemon Tree Hotels.
Disclaimer: This article is for information and education only and is not investment advice or a recommendation to buy or sell any security. Unlisted share prices are indicative. Unlisted shares carry high liquidity and valuation risk. Please consult a SEBI-registered investment adviser before investing.
Tags
Stay Connected, Stay Informed –
Don’t miss out on exclusive updates, market trends, and real-time investment opportunities. Be the first to know about the latest unlisted stocks, IPO announcements, and curated Fact Sheets, delivered straight to your WhatsApp.