


Mohan Meakin Limited - FY26 Results
Written by: Kratika Agrawal
Published: Sep 17, 2026
Updated: Sep 17, 2026
7 min read
Mohan Meakin Limited, established in 1855, headquartered at Mohan Nagar, Ghaziabad, is among India's earliest alcoholic beverage companies and manufacturer of Old Monk, which is considered the world's best selling dark rum. This company currently has four operational production units, including Solan Brewery (Himachal Pradesh), Kasauli Distillery, Bhankarpur (Punjab), and Mohan Nagar (Uttar Pradesh). Apart from this, it is also involved in the small-scale business of producing non-alcoholic foods and beverages, which include juices, cornflakes, wheat porridge, and vinegar. Since the liquor policies in India are controlled by state governments, Mohan Meakin relies to a large extent on licensed third parties for bottling its product. Shares of this company are listed on the Calcutta Stock Exchange, where there were no transactions during the year, and hence the pricing of shares is done in the grey market.
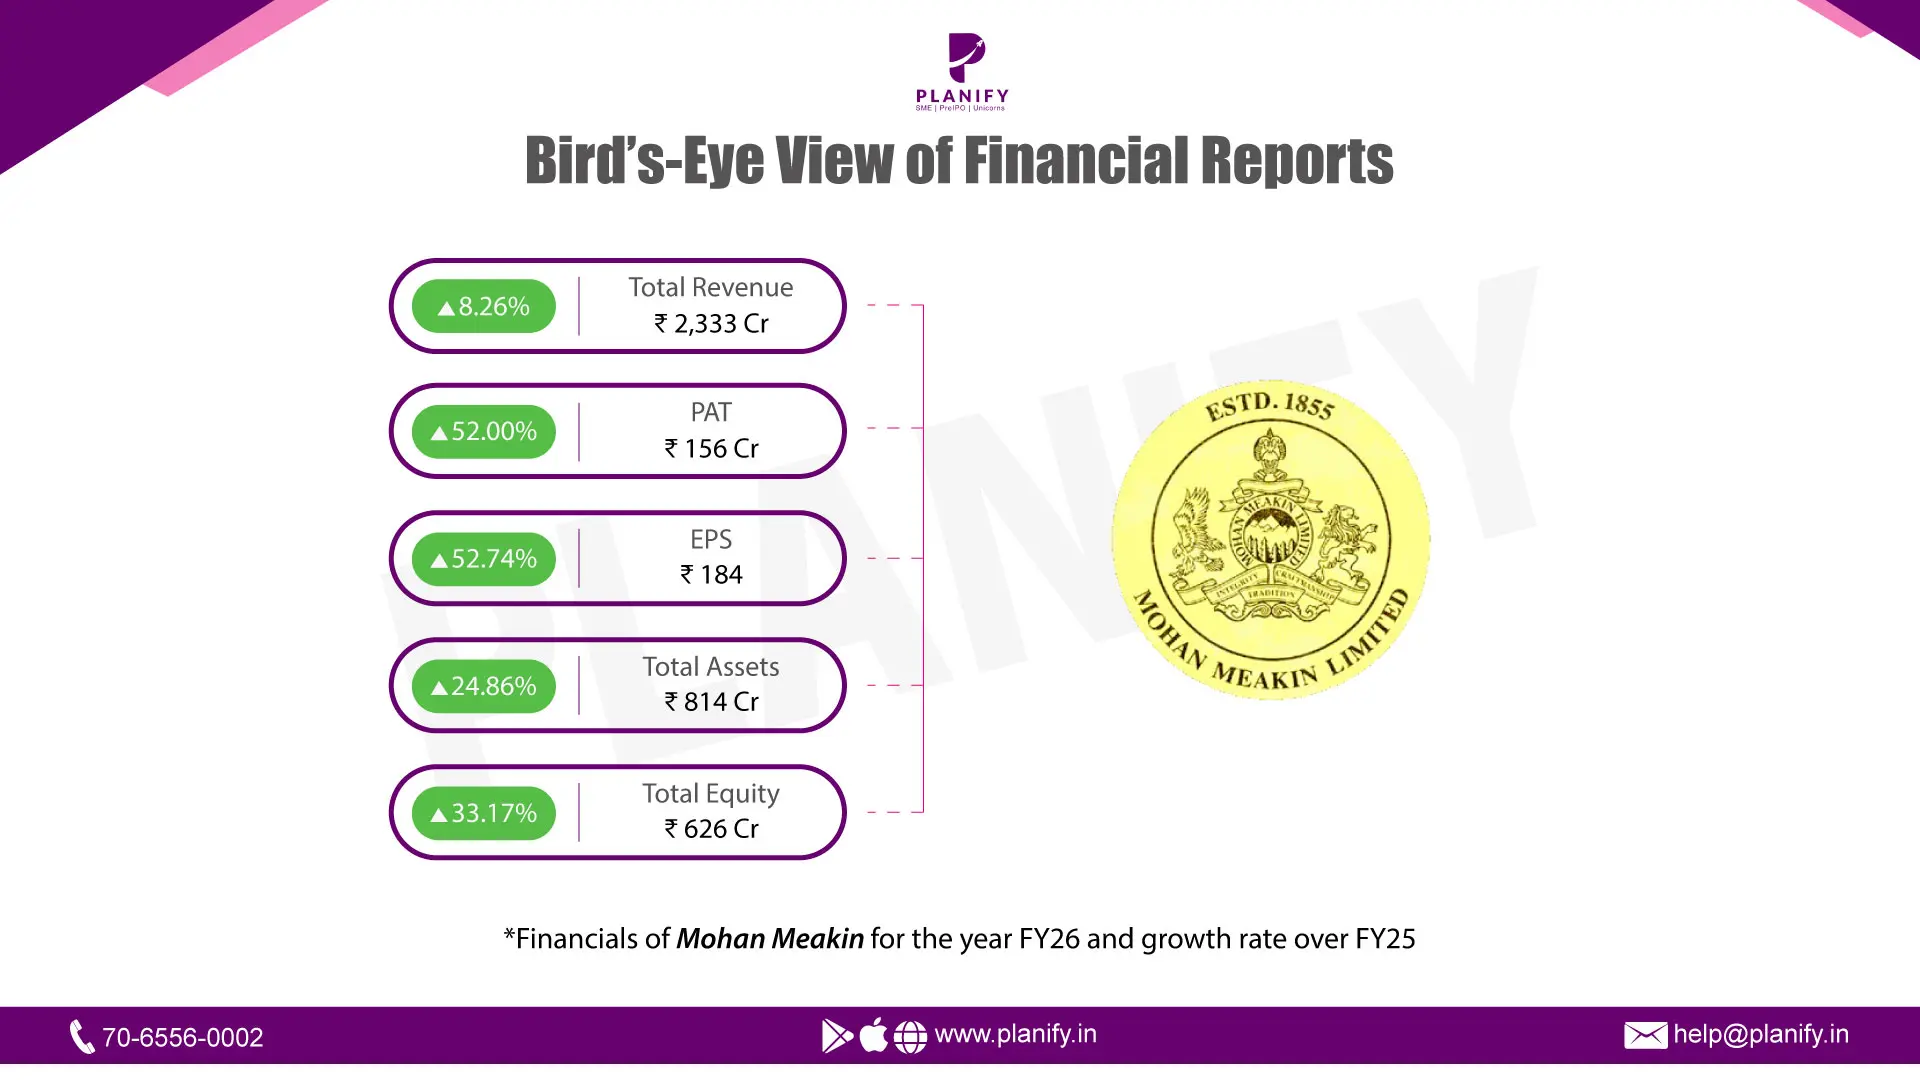
This report contains an analysis of the financial performance of Mohan Meakin Limited for the year ended March 31, 2026 vis-à-vis March 31, 2025. The year 2026 turned out to be a profitable one for the company with revenue from operations growing by a marginal 7.0% to ₹2,302 Cr while profit after tax increasing much faster at 52.7% to ₹157 Cr, driven by a massive swing in the excise duty expense line and a continuing shift in the revenue mix towards the sale of products in which the company did not invest in assets. This resulted in a substantial improvement in both the EBITDA margin (+2.6 pp) and the net profit margin (+2.0 pp). One interesting aspect about the company’s balance sheet is that it had almost no borrowings of ₹4.3 Cr against ₹398 Cr of cash, deposits and investments and was funded mainly by internal accruals.
1. Revenue, EBITDA, Net Profit & EPS Summary (₹ in Cr)
Particulars | FY26 | FY25 | Y-o-Y change |
Revenue from Operations | 2,302 | 2,151 | +7.0% |
EBITDA (pre-exceptional) | 219 | 149 | +47.0% |
EBITDA Margin | 9.5% | 6.9% | +2.6 pp |
Profit Before Tax | 209 | 138 | +51.4% |
Net Profit (PAT) | 157 | 103 | +52.7% |
NP Margin (NPM) | 6.8% | 4.8% | +2.0 |
EPS (₹) | 184.2 | 120.6 | +52.7% |
There was a modest increase of 7.0% in revenues, but there was a much steeper increase of 47.0% in EBITDA and 52.7% in PAT, which indicates that there was a real change in the profit generating machine. As mentioned earlier in Section 2, a significant reason for this difference is related to accounting treatment, where revenue includes excise duty and excise expenses have dropped substantially in FY26.
2. Revenue Mix & Excise Reconciliation (₹ in Cr)
2a. Revenue by source
Particulars | FY26 (₹ Cr) | FY26 (% of Rev) | FY25 (₹ Cr) | FY25 (% of Rev) |
|---|---|---|---|---|
Sale of manufactured goods | 693 | 30.1% | 991 | 46.0% |
Sale of traded goods | 1,520 | 66.0% | 1,093 | 50.8% |
Royalty income | 57.7 | 2.5% | 39.1 | 1.8% |
2b. Excise duty reconciliation
Particulars | FY26 (₹ Cr) | FY25 (₹ Cr) | Change |
|---|---|---|---|
Revenue from operations (as reported) | 2,302 | 2,151 | +7.0% |
Less: Excise duty (P&L expense) | 146 | 545 | −73.2% |
Revenue net of excise | 2,156 | 1,606 | +34.3% |
There was also some change in the composition of revenue towards the asset-light profile, with manufacturing done by the company coming down from 46.0% to 30.1% of revenues, while the procurement of the products from the independent bottlers went up from 50.8% to 66.0%, while royalty income – the most profitable source of revenues – grew the fastest at 47.6%. Given that the sales of the products are reported on an excise duty included basis (according to the company's accounting note), the manufactured and trade revenues contain excise duty whereas the royalty income does not, the shift in percentages should be seen as directional, not directly comparable. Additionally, when excluding the excise duty, the revenue growth comes in at 34.3%, not 7.0%, as the excise cost item dropped 73.2% year over year, a development which is not explained in the report but is reasonably related to higher volume of production through partnership facilities where the excise duty is paid by the bottlers, and not by Mohan Meakin.
3. Key Ratio Analysis
Ratio | FY26 | FY25 | YoY Change |
|---|---|---|---|
Net Profit Margin | 6.8% | 4.8% | +2.0 pp |
Return on Equity (ROE) | 28.6% | — | — |
Segment margin — alcoholic business | 9.8% | 7.3% | +2.5 pp |
Dividend payout ratio | ~1.4% | — | — |
Net cash / Net worth | ~63% | ~49% | +14 pp |
The ROE of 28.6% and the margin improvement in the core alcoholic segment from 7.3% to 9.8% indicate that capital efficiency is indeed on the right track, helped by the shift in revenues towards royalties and concentrates. Nevertheless, the company has not been able to convert capital efficiency into money for the shareholders: out of a profit of ₹157 Cr in FY26, the management suggested paying dividends at the rate of ₹2.50 per share, or a total amount of ~₹2.13 Cr, which represents a payout ratio of about 1.4%.
4. Valuation Snapshot
Metric | Value |
|---|---|
Shares outstanding | 85.08 lakh |
EPS (FY26) | ₹184.2 |
Book value per share | ₹735.9 |
Indicative unlisted price | ₹2,300–2,600 |
P/E (at ~₹2,450) | ~13.3x |
P/B | ~3.3x |
Net cash per share | ~₹463 |
As there are no share quotations on the Calcutta Stock Exchange in FY26, price discovery takes place in the unlisted market where the last trades would indicate a market capitalization of about ₹2,000–2,200 Cr. The company trades at a P/E ratio of about 13.3 and Price/Book ratio of 3.3 on the basis of an indicative price of ₹2,450. Once adjusted for the net cash of ₹463 per share, the operating business gets a valuation multiple of 11x of earnings, which is a substantial discount as compared to that of listed liquor companies due to lack of liquidity, absence of analyst coverage, related party components in earnings, and extremely low dividends.
Stay Connected, Stay Informed –
Don’t miss out on exclusive updates, market trends, and real-time investment opportunities. Be the first to know about the latest unlisted stocks, IPO announcements, and curated Fact Sheets, delivered straight to your WhatsApp.


Planify Enterprises Private Limited
Planify Capital Limited
Licensed By




Mutual Fund License No.:
ARN-164419
IRDA Code (1):
ABLIC1003123454
IRDA Code (2):
ABLIC1003131639
Startup India Certificate No.:
DIPP93786
Other Websites


ⓒ 2016-2026 Planify. All rights reserved, Built with
in India


