Quality Enviro Engineers Limited: FY26 Results
Kratika Agrawal
Associate Financial AnalystFinancial Analyst at Planify with CFA L2 credentials, focused on valuation modeling and identifying growth opportunities across unlisted and pre-IPO equities.
Category
Quality Enviro Engineers Limited (QEE), established on May 6, 2016, and having its headquarters at Sahibabad, Ghaziabad, develops and produces municipal cleaning machinery, including sewer suction machines, road sweepers, anti-smog guns, sky lifts, water tankers, and vehicles. The company owns two factories in Ghaziabad with a total capacity of about 300 machines annually. Currently, the company is preparing for a SME IPO after its transformation from a private limited company and expansion of the board and authorized capital in 2026.
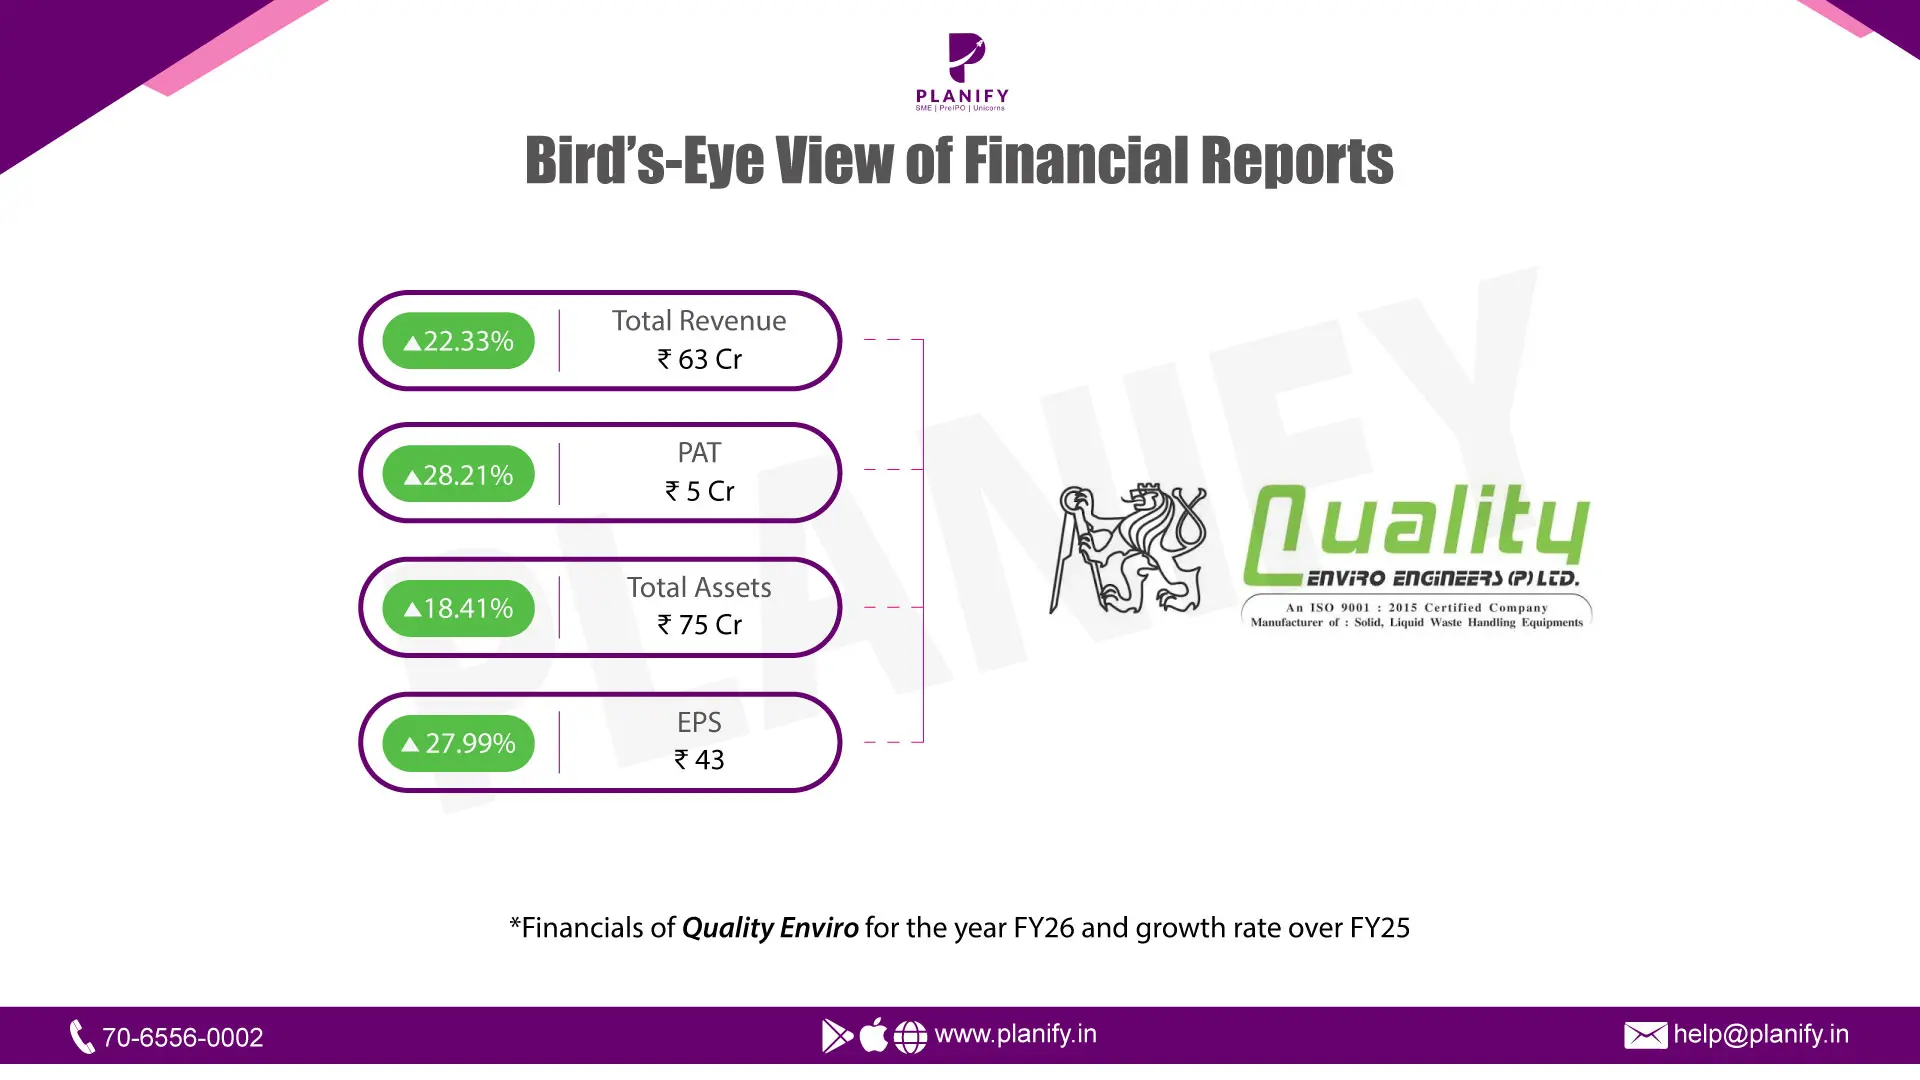
The following report is devoted to the presentation of the financial performance of Quality Enviro Engineers Limited for the year ending on March 31, 2026, relative to FY25, based on the annual report of the company. All amounts are stated in ₹ Crores. The year 2026 became another period of stable and profitable growth for QEE, since revenue increased by 22.3% to ₹63.0 Cr, while net profit increased by 28.2% to ₹5.0 Cr, completing a four-year period during which profit has grown faster than revenue. However, the operating cash flow remained negative for the second consecutive year, as growth was mainly funded through increasing inventory, receivables and short-term bank borrowing rather than internally generated cash.
1. Revenue, EBITDA & Net Profit Summary (₹ in Cr)
Particulars | FY26 | FY25 | YoY Change |
Revenue | 63.0 | 51.5 | +22.3% |
EBITDA | 6.69 | 5.97 | +11.7% |
EBITDA Margin | 10.6% | 11.7% | -1.0 pp |
Net Profit | 5.0 | 3.9 | +28.2% |
NP Margin | 7.9% | 7.6% | +0.4 pp |
Revenue growth witnessed a sharp uptick in FY26 following a bumpy ride over the previous three years (revenue was down in FY24). The growth in net profit outpaced that in revenue. In fact, net profit has been growing at around 25% per annum during FY23–FY26, compared to revenue that has grown by only 8%. However, some of the growth in profit in FY26 is accounted for by a once-off “balances written back” amounting to ₹70 lakhs within other income, and not within the business itself.
2. Revenue Mix by Segment (₹ in Cr)
Segment | FY26 | FY25 |
Machines manufactured | 31.6 | 39.9 |
Goods traded | 8.6 | 1.1 |
Services | 22.8 | 10.3 |
Rental | — | 0.2 |
Total | 63.0 | 51.5 |
There was a significant change in the mix in the current fiscal year. The revenues from QEE’s own production machinery were down by 21%. At the same time, the revenues from services business nearly tripled and represent 36% of the total revenue, up from just 20% in the FY25. This is indicative of QEE's transition from machine sales to recurring operate-and-maintain business model.
3. Valuation & Key Ratios
Metric | Value |
Indicative unlisted price (Sep 2026) | ~₹118/share |
Implied market capitalisation | ~₹153 Cr |
P/E (on FY26 profit) | 30.31x |
Promoter holding | ~72% |
On an indicative basis, QEE is priced at 30x of FY26 EPS – far from being a low valuation for a small and dependent on tenders contract company that consumes its working capital; however, perhaps justified by the fact that the profit-growth rate of ~25% will continue.
Conclusion
QEE is a small family-run business, which has been enjoying a favorable policy environment with Swachh Bharat Mission 2.0, the ban on manual scavenging, and air quality initiatives in North India boosting its sales. Profit growth has been genuine and sustained, while the trend toward services-based income shows a business model that is becoming more sticky. The primary overhang is related to cash flow management issues, as seen from two consecutive years of negative operating cash flow, increased accounts receivables and inventory, as well as increasing use of short-term banking loans. The problem with the company is not about securing tenders but about collecting payments. Items of contingent nature to track are a pending dispute of ₹83 lakh with Kanpur Nagar Nigam, older GST demands pending appeal, and ₹7.7 Cr transferred into the personal account of the MD in FY26.
Source: Quality Enviro Annual report FY26
Tags
Stay Connected, Stay Informed –
Don’t miss out on exclusive updates, market trends, and real-time investment opportunities. Be the first to know about the latest unlisted stocks, IPO announcements, and curated Fact Sheets, delivered straight to your WhatsApp.