Quality Enviro Engineers: Profits Up, Cash Tight
Kratika Agrawal
Associate Financial AnalystFinancial Analyst at Planify with CFA L2 credentials, focused on valuation modeling and identifying growth opportunities across unlisted and pre-IPO equities.
Category
QEE was set up in 2016. It manufactures municipal cleansing equipment in three categories (solid waste, liquid waste, and air pollution) from dustbins worth ₹2,200 to ₹50 lakh truck-mounted road sweepers at two factories in Ghaziabad. It is more of an assembler and fabricator company rather than a heavy manufacturer; its entire fixed assets amount to only about ₹4 crore. Its buyers are municipal corporations and urban local bodies; all revenue is generated within India.
Its sales mix is changing. Sales of its own machines have declined from ₹39.9 crore in FY25 to ₹31.6 crore in FY26, but services increased from ₹10.3 crore to ₹22.8 crore and trading from ₹1.1 crore to ₹8.6 crore. Currently, service sales constitute about 36% of revenue. Assuming it continues like that, it would be higher-quality revenue compared to one-time tender wins, since maintenance and operation of the machine is continuous.
The financials
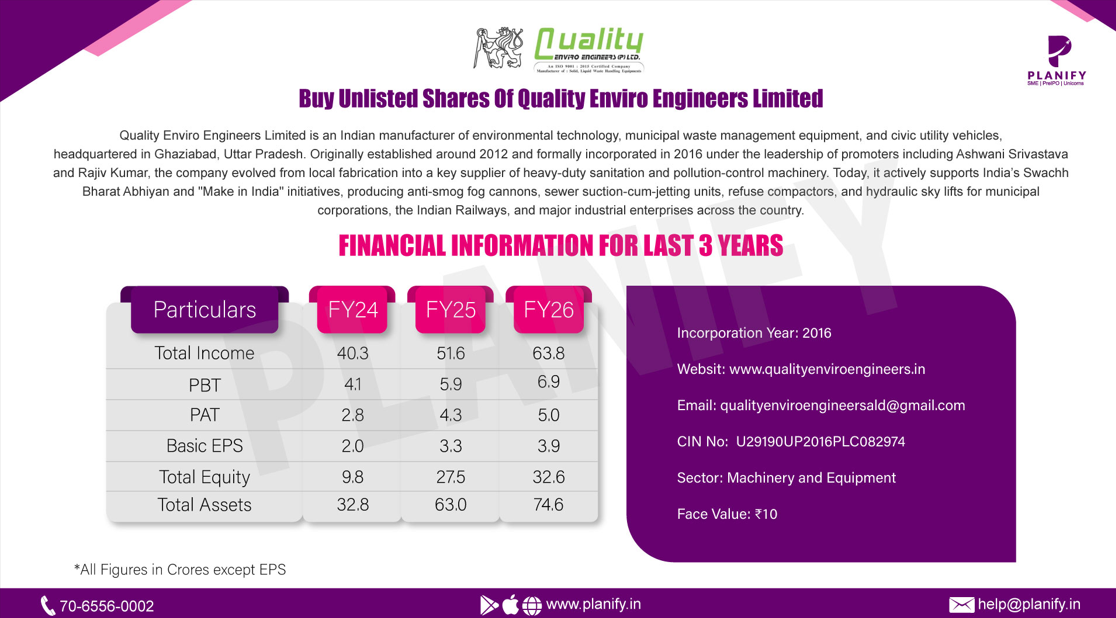
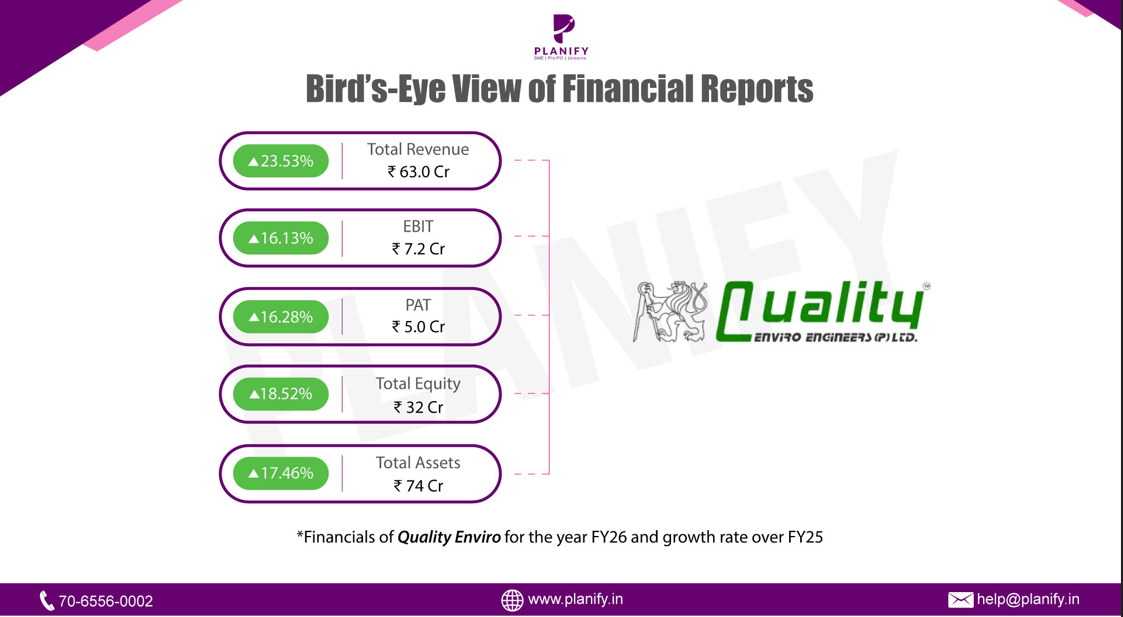
The revenue figures for FY23, FY24, FY25, and FY26 were ₹49 crore, ₹40 crore, ₹51 crore, and ₹63 crore respectively. The EBITDA figures for these years stood at ₹4 crore, ₹5 crore, ₹6 crore, and ₹7 crore respectively. The net profits for these years were ₹2.57 crore, ₹2.82 crore, ₹4.3 crore, and ₹5.03 crore.
Margin figures:
FY23 | FY24 | FY25 | FY26 | |
EBIT margin | 9.2% | 12.3% | 12.0% | 11.5% |
Net margin | 5.2% | 7.0% | 8.3% | 7.9% |
There are two key points here:
- Margins are stable, not growing. Margins are at 10–12%, declining in FY26.
- Net profit grows by 16%. This is a characteristic feature for firms based on tenders.
The cash conversion problem
This is the core of the problem. Operating cash flow was negative for both years: –₹8.8 crore in FY25 and –₹1.7 crore in FY26. This is nearly ₹10.5 crore in cash burn while making a profit of ₹9.3 crore.
The reason is the working capital. The increase in inventory from ₹1.1 crore to ₹14.4 crore, which consists mainly of partially completed machines, and the rise in receivables to ₹33.6 crore, which represents over half the revenues, is supplemented by a HDFC overdraft of ₹11.2 crore.
₹33.6 crore of receivables against ₹63.0 crore of revenues gives around 195 days of sales outstanding. Even for municipal accounts, this is a lengthy period. Receivables in this amount are more than five times the annual EBITDA of the company. Until this changes into cash, profits are not meaningful at all.
Governance flags
There is also the case of the ₹83 lakh dispute with Kanpur Nagar Nigam over sewer jetting machines that have not been paid for over three years now and are undergoing mediation, with no provision made. The most indicative is the dispute of ₹83 lakh with Kanpur. It is a real-life example of the receivables risk mentioned earlier, which is not provided against a profit base of ₹5 crore.
The ownership by promoters is high. The promoter family holds about 72%. This is typical for an SME, but the fact of independent directors and audit committee’s appointment in August 2026 makes them more relevant.
Valuation
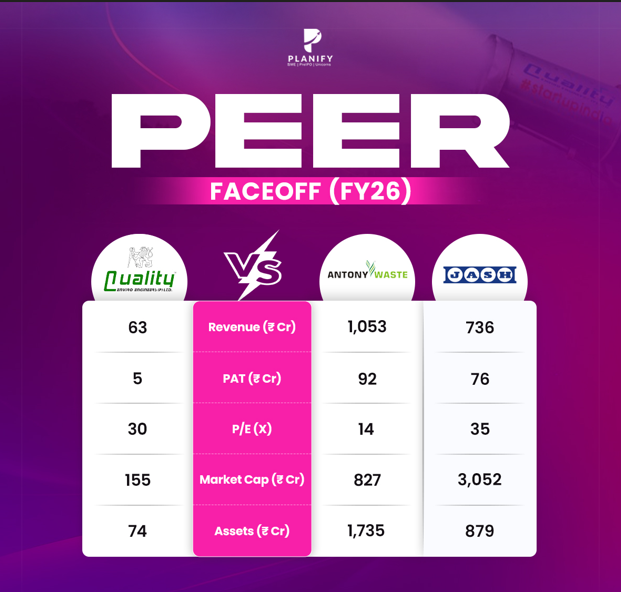
This unquoted value pegs QEE at around ₹155 crores, taking into consideration an indicative price around ₹120 per share after the issuance of 10:1 stock split. This implies an earnings multiple of 30.95x.
For an EBIT margin of ~11%, negative operating cash flow and government customers, this would be the complete valuation. This would be true only when the profit growth remains around 16% compounded and the working capital situation improves. The valuation for the May 2024 private equity round with a pre-bonus price of ₹551.20 was ₹65 crores, which is a growth of 1.38x in the last two years with negative operating cash flow.
Growth drivers
The demand backdrop is real:
- Swachh Bharat Mission (Urban) 2.0 was allocated ₹1,41,600 crore, but its official term expires on October 1, 2026, and it’s anybody’s guess about what will come next.
- Subsidies for mechanized cleaning of sewers are offered as they replace manual scavenging, while the National Clean Air Programme applies to Ghaziabad, Noida, and many more NCR towns close to QEE.
- The trend for municipal corporations to buy machines with drivers instead of the machines themselves is consistent with QEE’s growing revenue from services.
It could be dangerous because the policies are lumpy and tender-based. Any mismatch between budget cycles will affect the receivables and orders simultaneously.
IPO status
The draft offer document for the BSE SME listing filing is made on 30 September 2026. The DRHP needs to answer many unanswered issues, such as use of proceeds (if it will be used for repayment of overdraft and financing of working capital, then it answers the core issue), audited cash flow, concentration of customers, and related party issues.
Verdict
QEE is a small company leveraging a strong theme, underpinned by a solid policy, with increasing profitability and an exciting trend towards services. However, there is significant heterogeneity in the nature of its profitability. It has negative cash flows, very long receivables, unresolved disputes without allowance, and questionable governance structures. The valuation has factored in success.
What would alter my opinion in a favorable way: Days sales outstanding below 120 days, positive cash flows from operations, services maintaining at more than one-third of revenues, and clean disclosures of related party transactions.
What would make me more cautious: The funds raised through IPO mostly going to promoter’s liquidity, increase in receivables, or a policy void following SBM-U 2.0.
Tags
Stay Connected, Stay Informed –
Don’t miss out on exclusive updates, market trends, and real-time investment opportunities. Be the first to know about the latest unlisted stocks, IPO announcements, and curated Fact Sheets, delivered straight to your WhatsApp.