Behind the ₹156 Crore PAT: Dissecting Renfra Energy's Cash Burn and Working Capital Drag
Kratika Agrawal
Associate Financial AnalystFinancial Analyst at Planify with CFA L2 credentials, focused on valuation modeling and identifying growth opportunities across unlisted and pre-IPO equities.
Category
Profit is easy to celebrate in an IPO filing. Cash is harder to find. Renfra Energy, a Tamil Nadu solar and wind EPC contractor, shows why that gap matters for investors.
A Rapid Climb
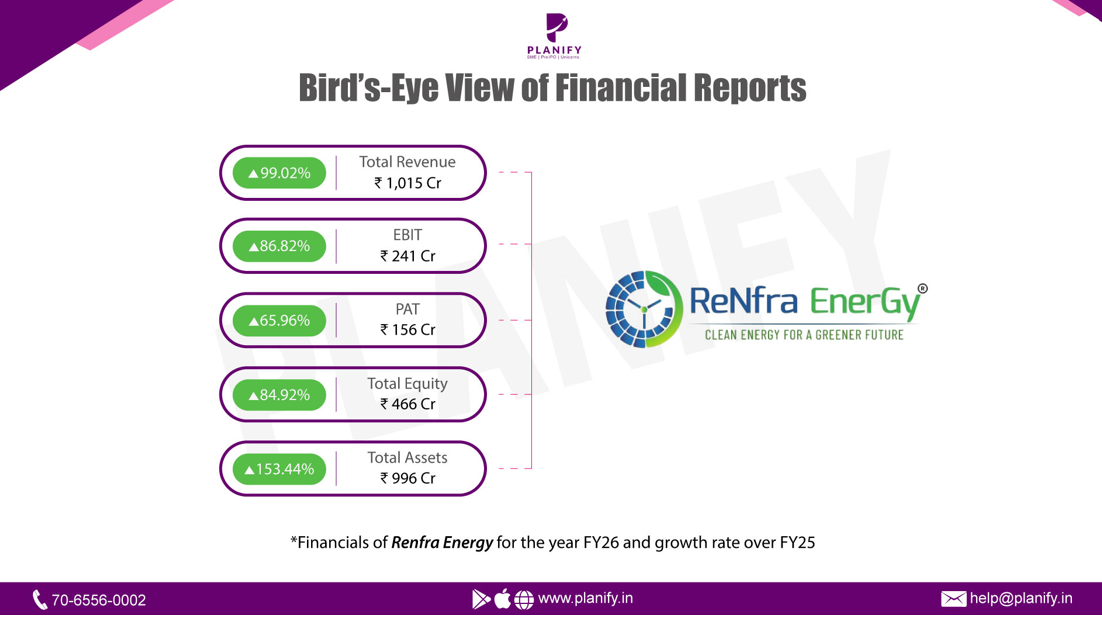
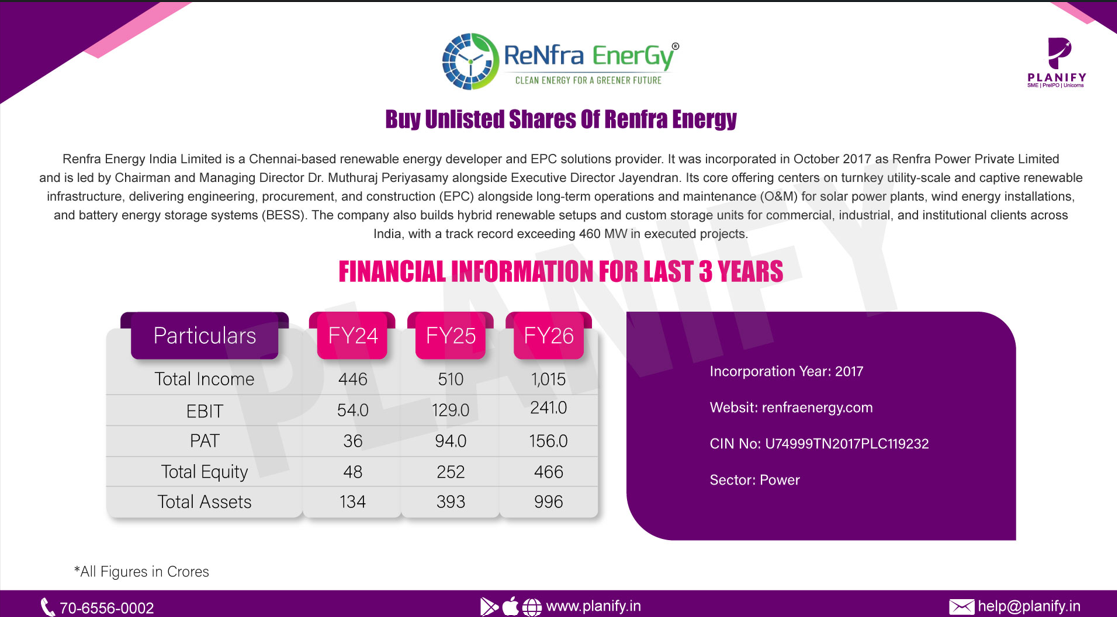
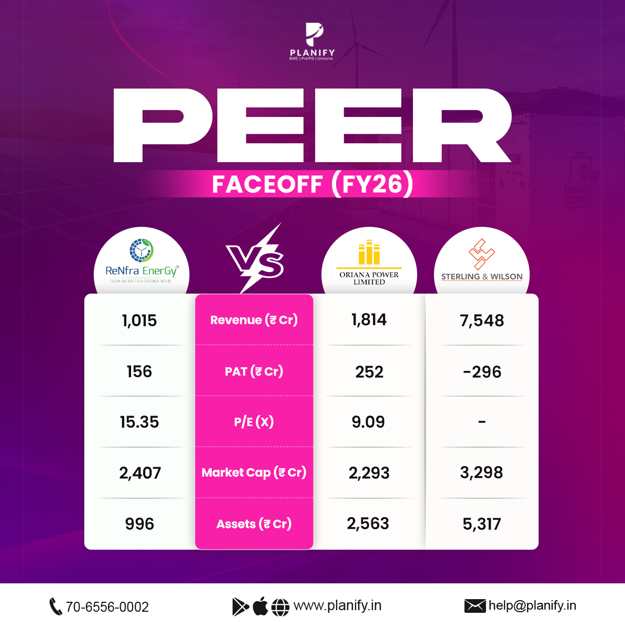
The revenue from operations increased from ₹446 crore in FY24 to ₹510 crore in FY25 and ₹1,015 crore in FY26. During the same period, the profit after tax increased from ₹36 crore to ₹94 crore and then to ₹156 crore. EBITDA stood at ₹251 crore in FY26, which amounts to a margin of roughly 24%. Along with the income statement, the balance sheet too expanded in size: Total assets increased from ₹134 crore to ₹996 crore in two years.
EPS increased from ₹2.63 to ₹6.59 and then ₹9.51. ROE declined from 122% to 62% and then increased to 124%. Revenue nearly doubled in FY26 (roughly 98.5% Y-o-Y), while PAT increased by 66%. The finance cost increased to ₹34.04 crore in FY26.
PAT margin in FY24 was 8%, 18% in FY25 and 15% in FY26. The EBIT margin was 12%, 25% and 23%.
The IPO
The DRHP has been filed with SEBI on June 30, 2026, and the shares will be listed on BSE and NSE. The promoters Muthuraj Periyasamy (Chairman & MD) and Jayendran (ED) do not sell through the OFS. The promoters have a collective stake of 81.81%.
Why Profit and Cash Drift Apart
The EPC contractor is paid after spending and not before. The firm invests in panels, turbines and other equipment, pays its suppliers and holds inventories whereas the payment from customers depends on the completion of milestones. The working capital locked in the process increases with the increase in revenues.
This is evident in the FY26 figures provided by the company’s cash flow statement. The operating profit before the change in working capital of the company is ₹252 crore. However, the net cash used in operating activities is -₹119 crore after paying ₹53 crore in the form of direct taxes, as the increase in receivables, advances and other financial assets occurred. Last year the firm relied upon the equity of ₹109.54 crore besides borrowing and the same year the business relied on equity worth ₹57 crore.
Renfra ensures land availability and grid connection prior to getting any customer orders, making the execution faster but requiring upfront funding. The typical execution period ranges between 120 and 150 days for solar and 180 to 220 days for wind. Other risks include increasing receivable days and fixed price EPC contract margin exposure to cost overruns.
Wind Is The Variable To Watch
Solar has founded the firm. The firm has completed 32 projects in FY2026 which comprised 21 solar projects and 11 wind projects. The firm has 204.75 MW of projects in execution phase and 173.8 MW of commissioned capacity.
The experience is shallow. Renfra has executed 11 wind projects in FY26 compared with 2 projects in FY25 and zero projects in FY24. Projects relating to wind energy are relatively complicated compared to rooftop and ground-mounted solar projects; moreover, a long construction cycle locks in capital for a longer duration. If the proportion of wind continues to rise in the portfolio, working capital pressures may rise.
Concentration
The entire business operates from a single location. Renfra provides services to customers located in Tamil Nadu and Puducherry, and the solar and wind projects contributed to 98.36% of the total income during FY26. If there is any slow down in the demand for commercial and industrial activities or any changes in the policies of that region, then it would affect almost all areas. As of May 15, 2026, the company has Completed Projects with an aggregate installed capacity of 462.35 MW consisting of 412.85 MW of solar projects and 49.50 MW of wind projects, and ongoing Projects with an aggregate capacity of 139.10 MW consisting of 83.00 MW of solar power projects and 56.10 MW of wind power projects under different stages of execution.
What The Price Implies
The unlisted shares were quoted at ₹142 on 04 Nov 2026, which was just a dealer indicative quote and not a stock exchange price. The price band for the IPO has not yet been declared, and the company is waiting for approval from SEBI and other authorities.
With 16.95 crore of pre-IPO shares, ₹142 works out to ₹2,406 crore market cap, which would mean 14x FY26 EPS.
Tags
Stay Connected, Stay Informed –
Don’t miss out on exclusive updates, market trends, and real-time investment opportunities. Be the first to know about the latest unlisted stocks, IPO announcements, and curated Fact Sheets, delivered straight to your WhatsApp.